

Executive Summary Date: 2026-10-12
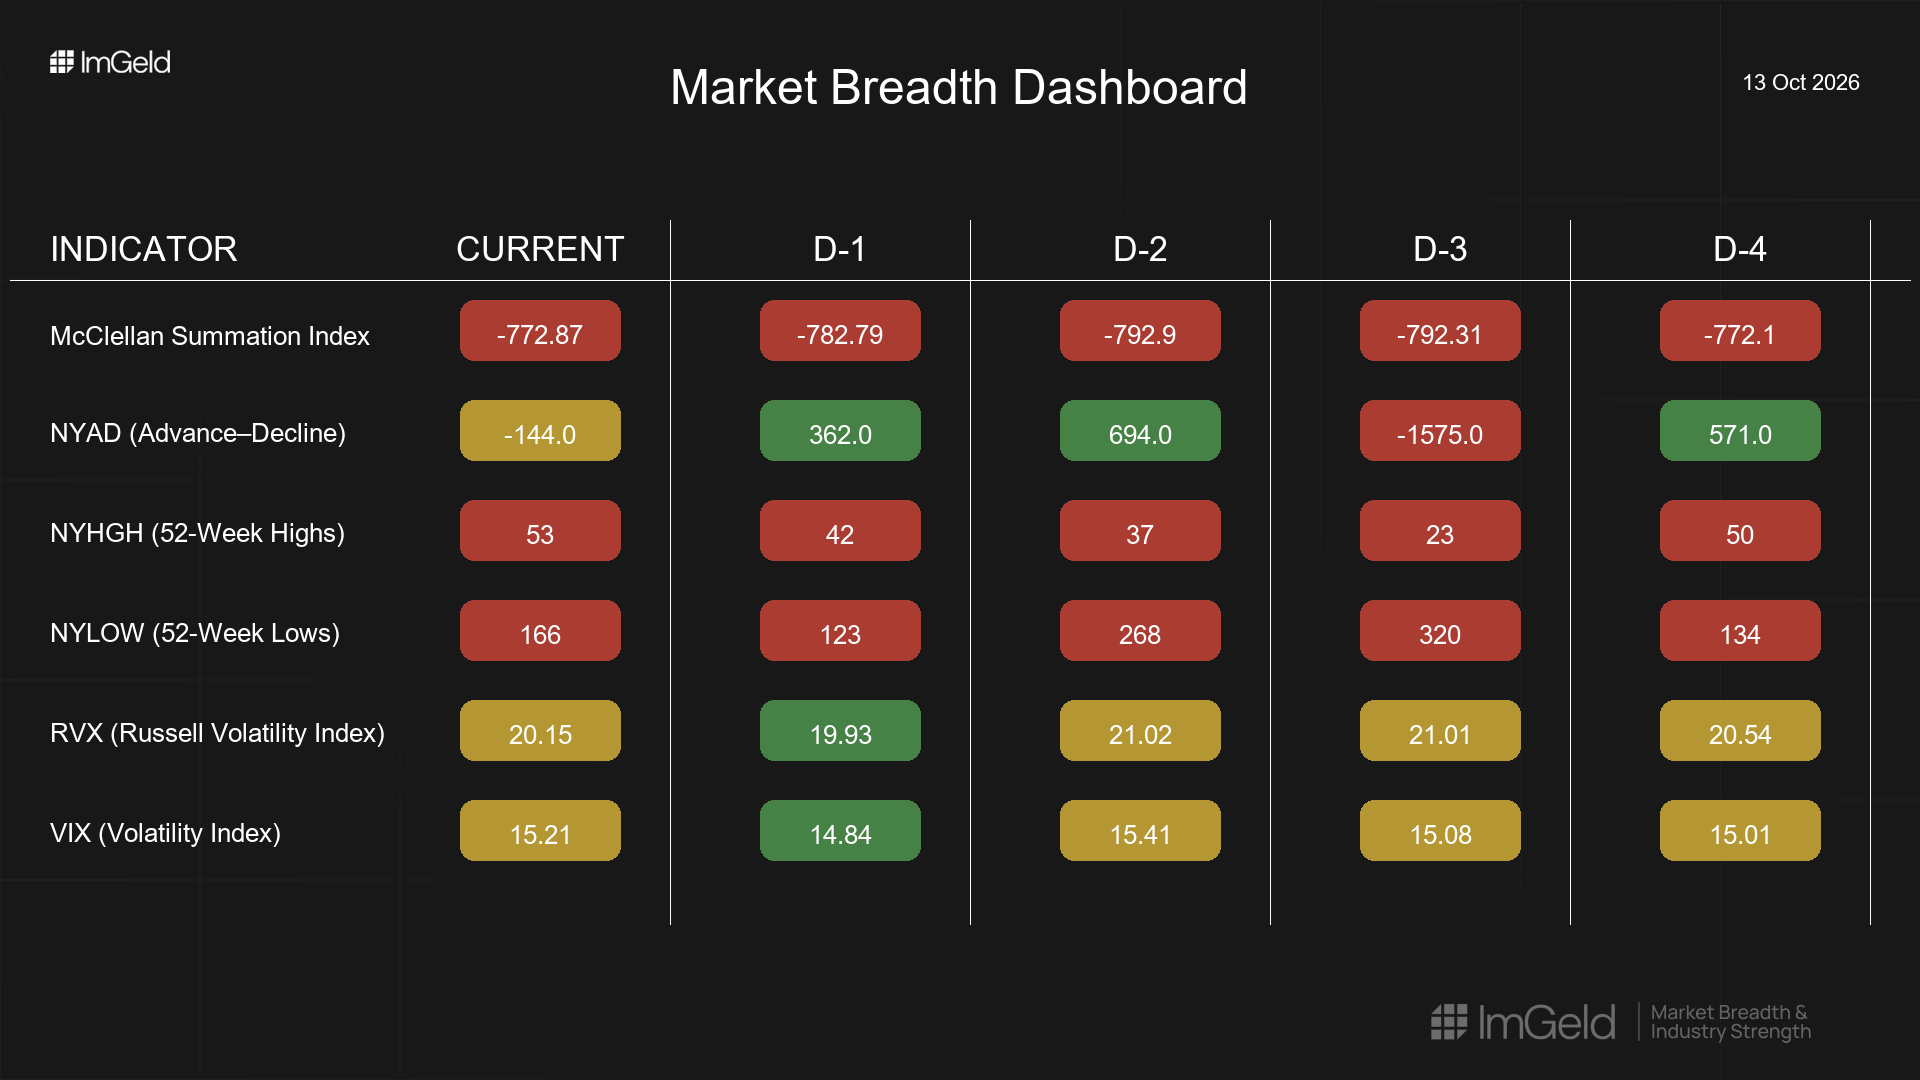
Breadth leans Tentative SHORT. NYSI (McClellan Summation Index) remains deeply negative but ticked higher over the last two sessions, hinting at early basing within a broader downtrend. NYAD (Advance–Decline Line) oscillated and finished slightly negative across five sessions, signaling inconsistent participation. VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) stayed range-bound near 15 and 20 respectively, indicating subdued risk premia with the potential for abrupt reversals.
Tactically, short opportunities remain valid in large-cap industries where rallies are failing and breadth is deteriorating. Any emerging long interest should be highly selective and confined to mid-cap industries demonstrating rising new-high participation and consistent positive advance–decline days.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is attempting to broaden modestly, yet remains narrow in absolute terms as new lows continue to outnumber new highs on most days. Leadership is concentrated, with incremental improvement in new highs not yet translating into broad participation. Volatility is contained and mildly compressing, which raises the risk of sharp moves if breadth weakens again. A mild positive divergence is present with NYSI stabilizing while NYAD remains mixed. Applying the five-day consistency rule, signals remain mixed rather than consistent, so the pattern remains in the tentative camp rather than firmly transitioning to accumulation.
Indicator Breakdown
NYSI (McClellan Summation Index) Structure declined into 10-09 and improved modestly on 10-12 and 10-13. Despite the uptick, levels remain deeply negative, consistent with a bearish regime that is attempting to base rather than reverse.
NYAD (Advance–Decline Line) Daily prints were +571, -1575, +694, +362, -144. This whipsaw profile reflects unstable participation, with a slight five-day net negative. Breadth strength is not yet durable.
NYHGH (New 52-Week Highs) Rising from 23 on 10-08 to 53 on 10-13 suggests tentative leadership expansion, though the absolute count remains modest. Improvement is incremental, not broad-based.
NYLOW (New 52-Week Lows) Spiked to 320 on 10-08, then moderated to 123–166. Downside pressure has eased but remains elevated versus new highs, indicating risk appetite is cautious and unfinished on the downside.
Volatility Regime VIX hovered around 15 and RVX around 20, with a stable spread and mild compression. This favors tactical patience and selectivity, with a propensity to sell strength rather than chase weakness, and to anticipate volatility re-expansion if breadth deteriorates.
Tactical Stance
Shorts: Remain focused on large-cap industries where breadth is failing and earnings dispersion is widening, such as semiconductors, consumer internet, and broadline retail, particularly into strength.
Longs: Only consider highly selective mid-cap opportunities within industries showing repeated positive advance–decline days and rising new highs, with strict risk controls.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.