

Executive Summary Date: 2026-11-12
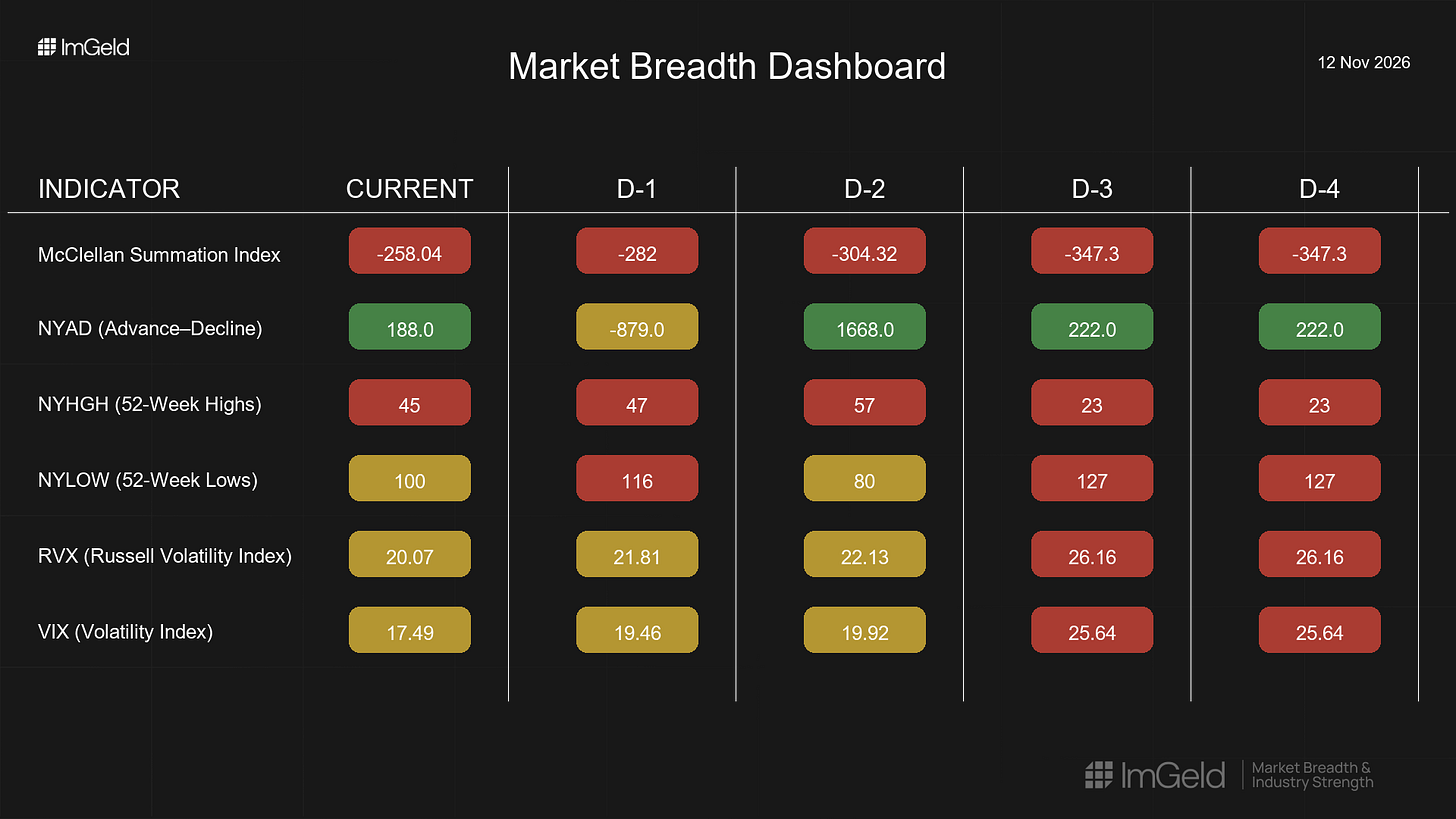
Breadth is attempting to repair: NYSI (McClellan Summation Index) rose for three straight sessions from deeply negative levels, while NYAD (Advance–Decline Line) remained choppy with a strong up-thrust followed by a sharp giveback and a mild positive close.
Volatility is compressing: VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) trended lower across the week, easing financial conditions at the margin.
Tactically: selective long opportunities are emerging in mid-cap industries where new highs are building and new lows are receding. Short setups remain valid in crowded large-cap leaders showing weakening breadth and mean-reversion risk. Execution requires high selectivity and disciplined risk control.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is modestly broadening: NYHGH advanced from low 20s to mid-40s/50s, while NYLOW eased versus the week’s start despite midweek stress. Leadership shows early rotation away from defensives toward growth- and rate-sensitive industries, yet it is not universally established given NYAD’s whipsaw. Volatility is firmly compressing as both VIX and RVX declined each day after the initial print, supportive of breakouts and squeezes but also raising the bar for follow-through. A mild divergence is present: NYSI is improving while daily NYAD remains mixed, implying cumulative breadth healing beneath noisy day-to-day readings. The five-day pattern signals early accumulation, not yet confirmed; improvement is firm in NYSI and volatility, but participation remains mixed.
Indicator Breakdown
NYSI (McClellan Summation Index)
Improving: flat to start, then three consecutive rises from -347.3 to -258.0. Structure is turning up from depressed levels but remains below zero; follow-through is required for a durable trend change.
NYAD (Advance–Decline Line)
Mixed participation: strong advance (11-10), sharp reversal (11-11), modest positive close (11-12). Breadth is volatile and not yet consistently supportive, indicating ongoing selectivity.
NYHGH (New 52-Week Highs)
Leadership expansion: highs climbed from 23 to 45–57, a constructive early sign, though absolute counts remain moderate.
NYLOW (New 52-Week Lows)
Downside pressure easing but unresolved: lows fell from 127 to 80 before stabilizing near 100. Risk appetite is improving, yet residual stress persists.
Volatility Regime
Firm compression: VIX declined from 25.6 to 17.5; RVX from 26.2 to 20.1. Lower volatility supports mid-cap breakouts and base resolutions, reduces expected downside tail risk, and raises the risk of short squeezes. Maintain tighter stops on shorts and demand price confirmation on longs.
Tactical Implications
Longs: prioritize mid-cap industries showing improving leadership and constructive bases, such as application software, building products, specialty finance, electrical components, and life science tools.
Shorts: focus on overowned large caps where breadth and momentum are deteriorating and mean-reversion risk is elevated, including defensive consumer platforms and integrated energy majors that failed to confirm highs.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.