

Executive Summary Date: 2026-09-23
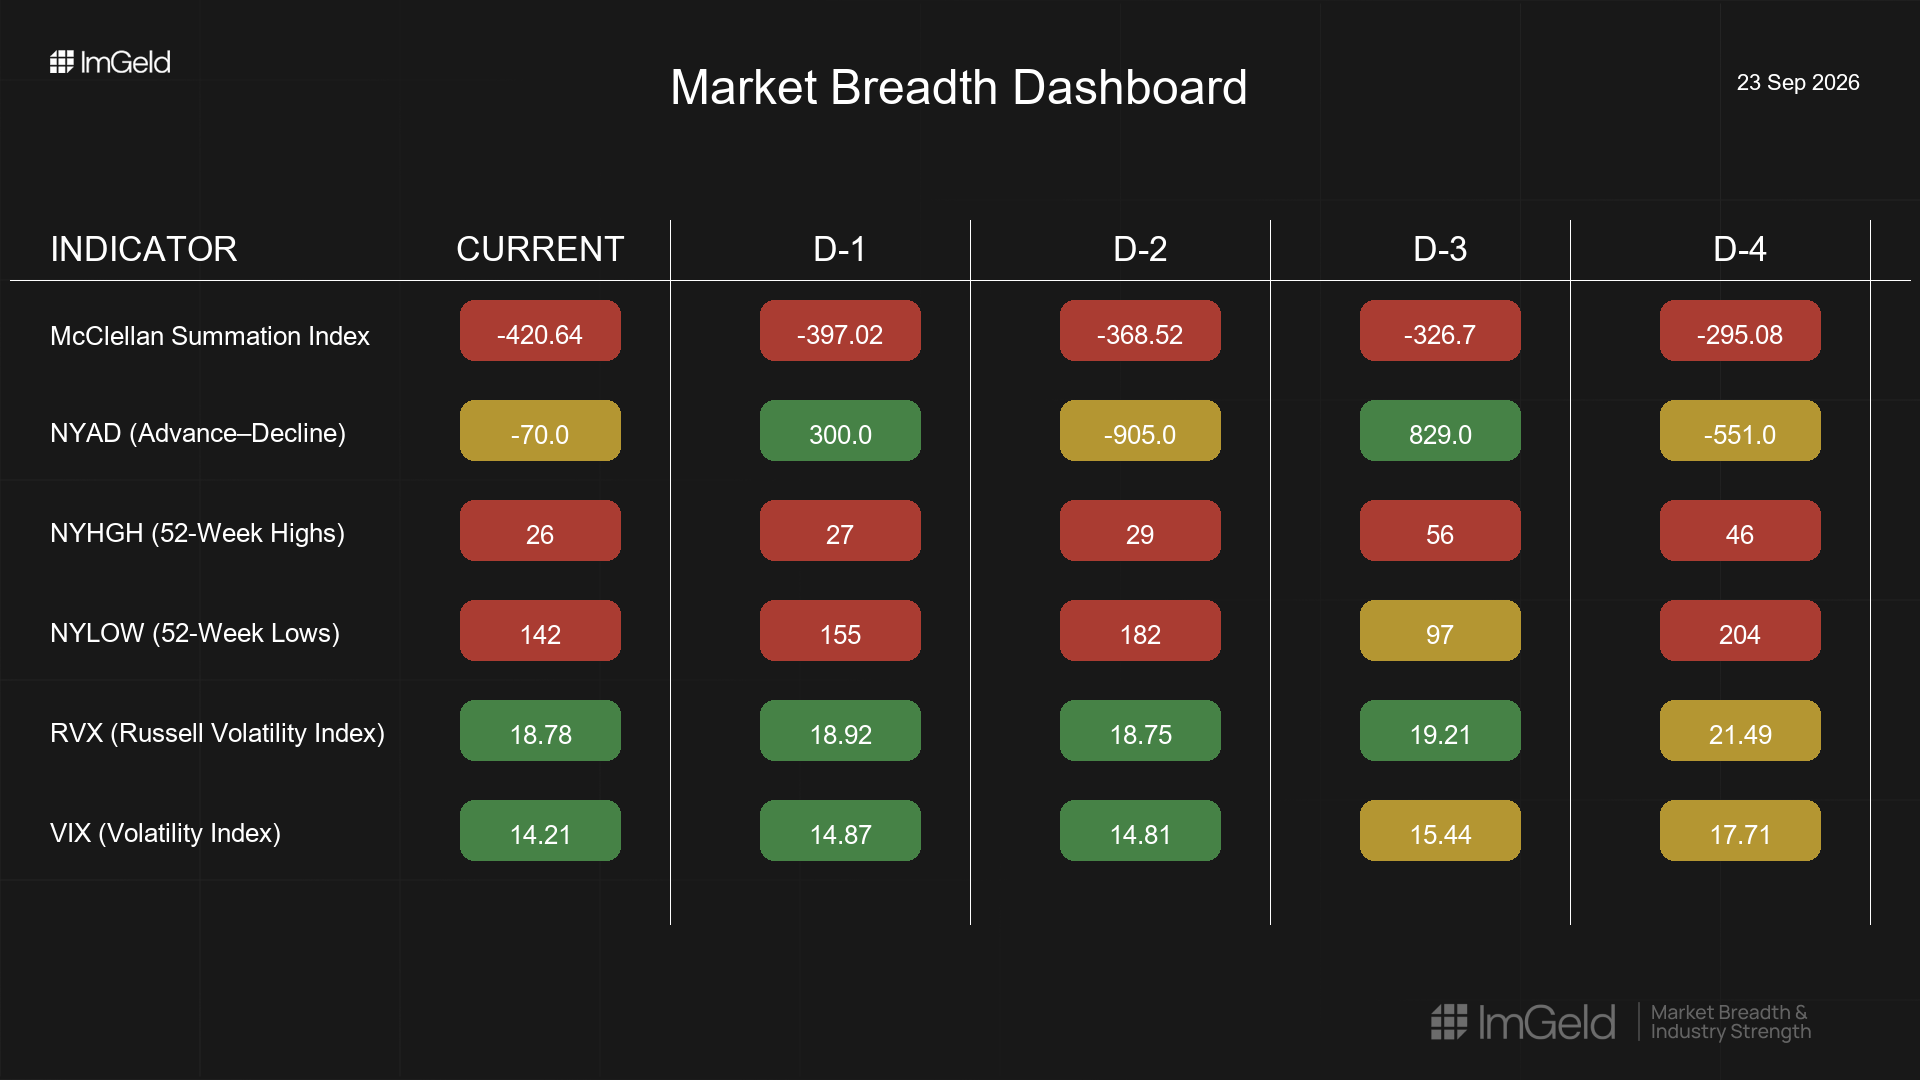
Breadth weakened across the last five sessions. NYSI (McClellan Summation Index) declined steadily, NYAD (Advance–Decline Line) was choppy with a negative net, and leadership narrowed as new highs contracted while new lows stayed elevated. VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) compressed, signaling complacency despite deteriorating breadth.
Tactical bias: tentative short. Long opportunities are limited to highly selective mid-cap industries showing relative resilience and improving internal metrics; confirmation is required. Short setups remain valid, particularly in crowded large-cap leadership and lagging cyclical industries; patience is warranted to sell strength given low volatility.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing, with leadership becoming more concentrated as new highs fall and new lows remain elevated. Volatility is firmly compressing, which can mask distribution and increase whipsaw risk for late entries. A clear divergence is present: NYSI is firmly deteriorating while NYAD oscillates, indicating rallies lack follow-through. By the five-day consistency rule, NYSI is firmly lower, volatility is firmly compressing, and participation remains mixed. The pattern points to continuation rather than early accumulation; near-term exhaustion risk rises only if lows contract meaningfully alongside breadth stabilization.
Indicator Breakdown
NYSI (McClellan Summation Index)
Structure: firmly declining for five consecutive sessions, from -295.08 to -420.64. Persistent downside momentum in aggregate breadth.
NYAD (Advance–Decline Line)
Daily participation: mixed and net negative over five days (-551, +829, -905, +300, -70). Three down days out of five indicate distribution pressure; advances are being faded.
NYHGH (New 52-Week Highs)
Leadership expansion: contracting from 56 to 26 after an early uptick. Leadership is thinning, consistent with narrowing participation.
NYLOW (New 52-Week Lows)
Downside pressure: elevated but easing from 204 to 142. Risk appetite remains subdued; any improvement is tentative until lows compress further and sustainably.
Volatility Regime
VIX (CBOE Volatility Index): 17.71 → 14.21.
RVX (Russell Volatility Index): 21.49 → 18.78.
Implications: volatility is compressing while breadth deteriorates, a setup prone to sharp reversal spikes. Prefer initiating shorts on strength and avoiding late entries on weakness.
Tactical Takeaways
Long: only consider highly selective mid-cap industries with improving relative strength and stabilizing internals (e.g., regulated utilities, insurance), and await confirmation.
Short: remain focused on rallies in crowded large-cap growth leadership and weaker mid-cap cyclicals (software, semiconductors, consumer discretionary industries with deteriorating breadth). Low volatility argues for patience and tighter risk controls.Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.