

Executive Summary Date: 2026-10-01
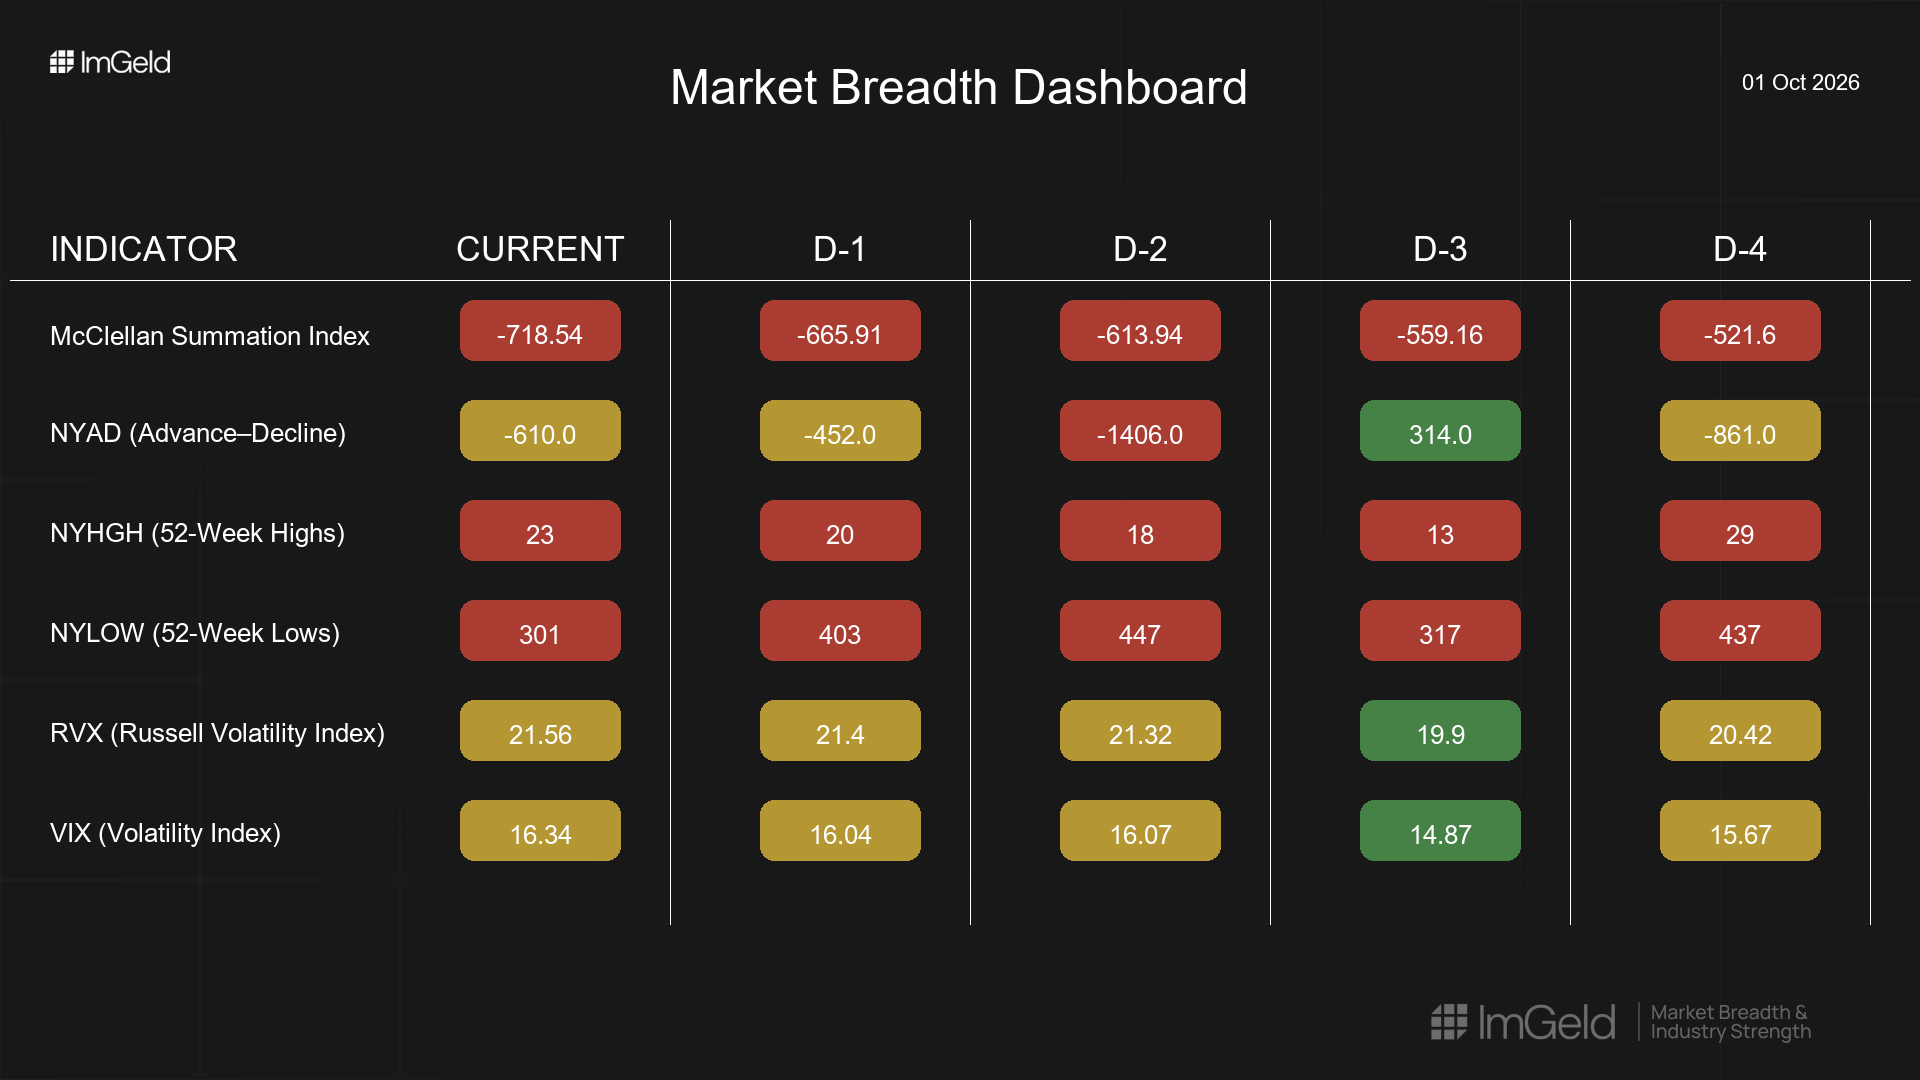
Breadth deteriorated over the last five sessions. NYSI (McClellan Summation Index) fell steadily to new lows, while NYAD (Advance–Decline Line) printed four negative days out of five. Volatility firmed, with VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) both trending higher. The bias remains a tentative short: weak bounces are sellable, and selectivity is high. Any long exposure should be confined to mid-cap names within industries showing improving internal thrust and relative strength. Large caps are suitable only for short setups where overextension and weak breadth persist.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing as new highs remain scarce and new lows stay elevated despite some late-week easing. Leadership is becoming more concentrated, with little evidence of broadening within winning cohorts. Volatility is mildly expanding, consistent with distribution rather than repair. There is no constructive divergence: NYSI declined each day while a one-day NYAD uptick failed to carry. By the five-day consistency rule, breadth deterioration is firmly in place, volatility expansion remains, and the pattern signals continuation rather than early accumulation. Expect rallies to struggle without a sustained drop in new lows and a multi-day positive NYAD sequence.
Indicator Breakdown
NYSI (McClellan Summation Index)
Firmly declining across all five sessions, confirming a persistent negative structure and ongoing net selling pressure beneath the surface.
NYAD (Advance–Decline Line)
Weak daily participation: four negative prints (9/25, 9/29, 9/30, 10/01) versus one positive (9/28). The lone positive day was isolated and did not shift trend, indicating breadth remains under pressure.
NYHGH (New 52-Week Highs)
Leadership expansion is limited, fluctuating at low double-digits (13–29). No evidence of a durable leadership broadening that typically accompanies sustainable advances.
NYLOW (New 52-Week Lows)
Downside pressure remains elevated (301–447) but eased into the latest print. Risk appetite is still impaired; a decisive improvement would require multiple days with materially lower new lows.
Volatility Regime
VIX rose from 14.87 to 16.34 and RVX from 19.90 to 21.56, a controlled but persistent expansion. This favors selling strength, managing gross exposure tightly, and anticipating intraday reversals. Elevated RVX versus VIX underscores higher fragility in smaller capitalization cohorts.
Tactical takeaways: Maintain a cautious short bias. Large-cap indices and crowded growth industries remain appropriate on the short side into strength. Potential long candidates are scarce and should be limited to mid-cap names within industries exhibiting improving breadth, rising relative strength, and resilient price action versus equal-weight peers.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.