

Executive Summary Date: 2026-11-04
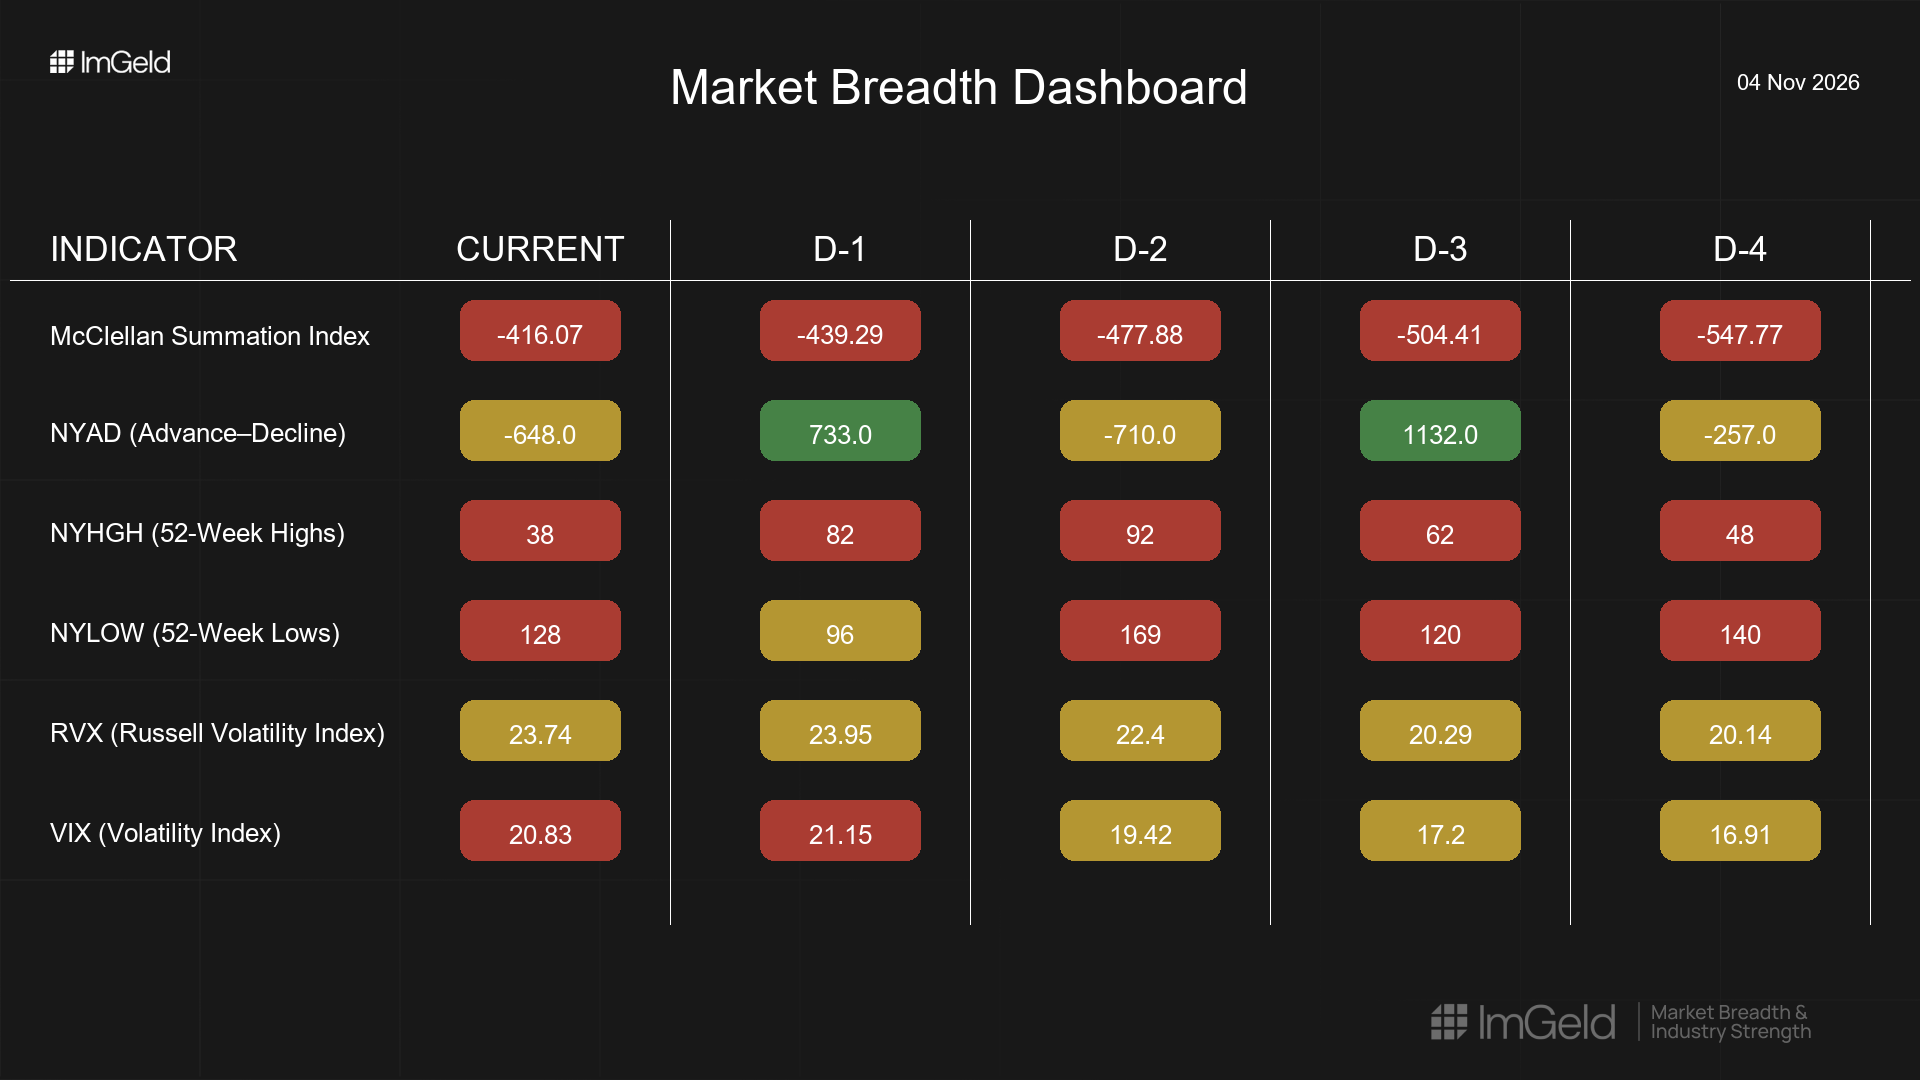
Breadth improved but remains fragile over the last five sessions. NYSI (McClellan Summation Index) rose steadily from -548 to -416, signaling firming internal momentum despite staying below zero. NYAD (Advance–Decline Line) alternated sharply between positive and negative days, netting positive over five sessions but lacking persistence. Volatility expanded: VIX (CBOE Volatility Index) advanced from 16.9 to 20.8 and RVX (Russell Volatility Index) from 20.1 to 23.7, indicating rising risk premia and tighter risk budgets.
Tactically, early long opportunities may be emerging in select mid-cap industries showing persistent relative strength and lower new-low incidence. Short setups remain valid in large caps where leadership is deteriorating and volatility is pressuring valuations. Selectivity is high; stagger entries and maintain disciplined risk controls.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is not broadly improving: leadership attempted to widen mid-period but narrowed into today, with NYHGH (New 52-Week Highs) falling back and NYLOW (New 52-Week Lows) remaining elevated. Leadership appears more concentrated, not rotating broadly. Volatility is expanding across both large-cap and small/mid universes. A divergence exists: NYSI is firmly improving while NYAD remains mixed, suggesting early accumulation underneath choppy day-to-day flows. Applying the five-day consistency rule: NYSI is firmly improving; NYAD remains mixed; volatility is firmly expanding. The five-day pattern signals tentative early accumulation, not a confirmed trend.
Indicator Breakdown
NYSI (McClellan Summation Index) Structure improved each day (-547.77 to -416.07). The upturn is constructive but still sub-zero, consistent with repair rather than a confirmed advance.
NYAD (Advance–Decline Line) Daily participation swung: -257, +1132, -710, +733, -648. Two outsized positive days were offset by three negatives, indicating breadth has not turned persistent.
NYHGH (New 52-Week Highs) Rallied to 92 on 11/02 and 82 on 11/03, then contracted to 38 on 11/04. Leadership expansion stalled, implying fewer names carrying upside.
NYLOW (New 52-Week Lows) Remained elevated (140, 120, 169, 96, 128). Downside pressure persists, capping risk appetite and arguing for careful position sizing.
Volatility Regime VIX climbed to the low-20s; RVX moved into the mid-20s. The expansion points to larger intraday ranges and higher gap risk. Tactically, emphasize staggered entries, wider but pre-defined stops, and a bias toward relative-strength mid-cap industries for longs while maintaining large-cap shorts where deterioration is clearest.
Tactical Implementation
Longs: Focus exclusively on mid-cap industries demonstrating improving multi-day advance–decline, stable new-highs breadth, and resilient relative strength on pullbacks.
Shorts: Large-cap laggards with contracting new-highs participation and sensitivity to volatility remain actionable on bounces.atforms, semiconductors, consumer platforms), favoring fades into strength.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.