

Executive Summary Date: 2026-08-04
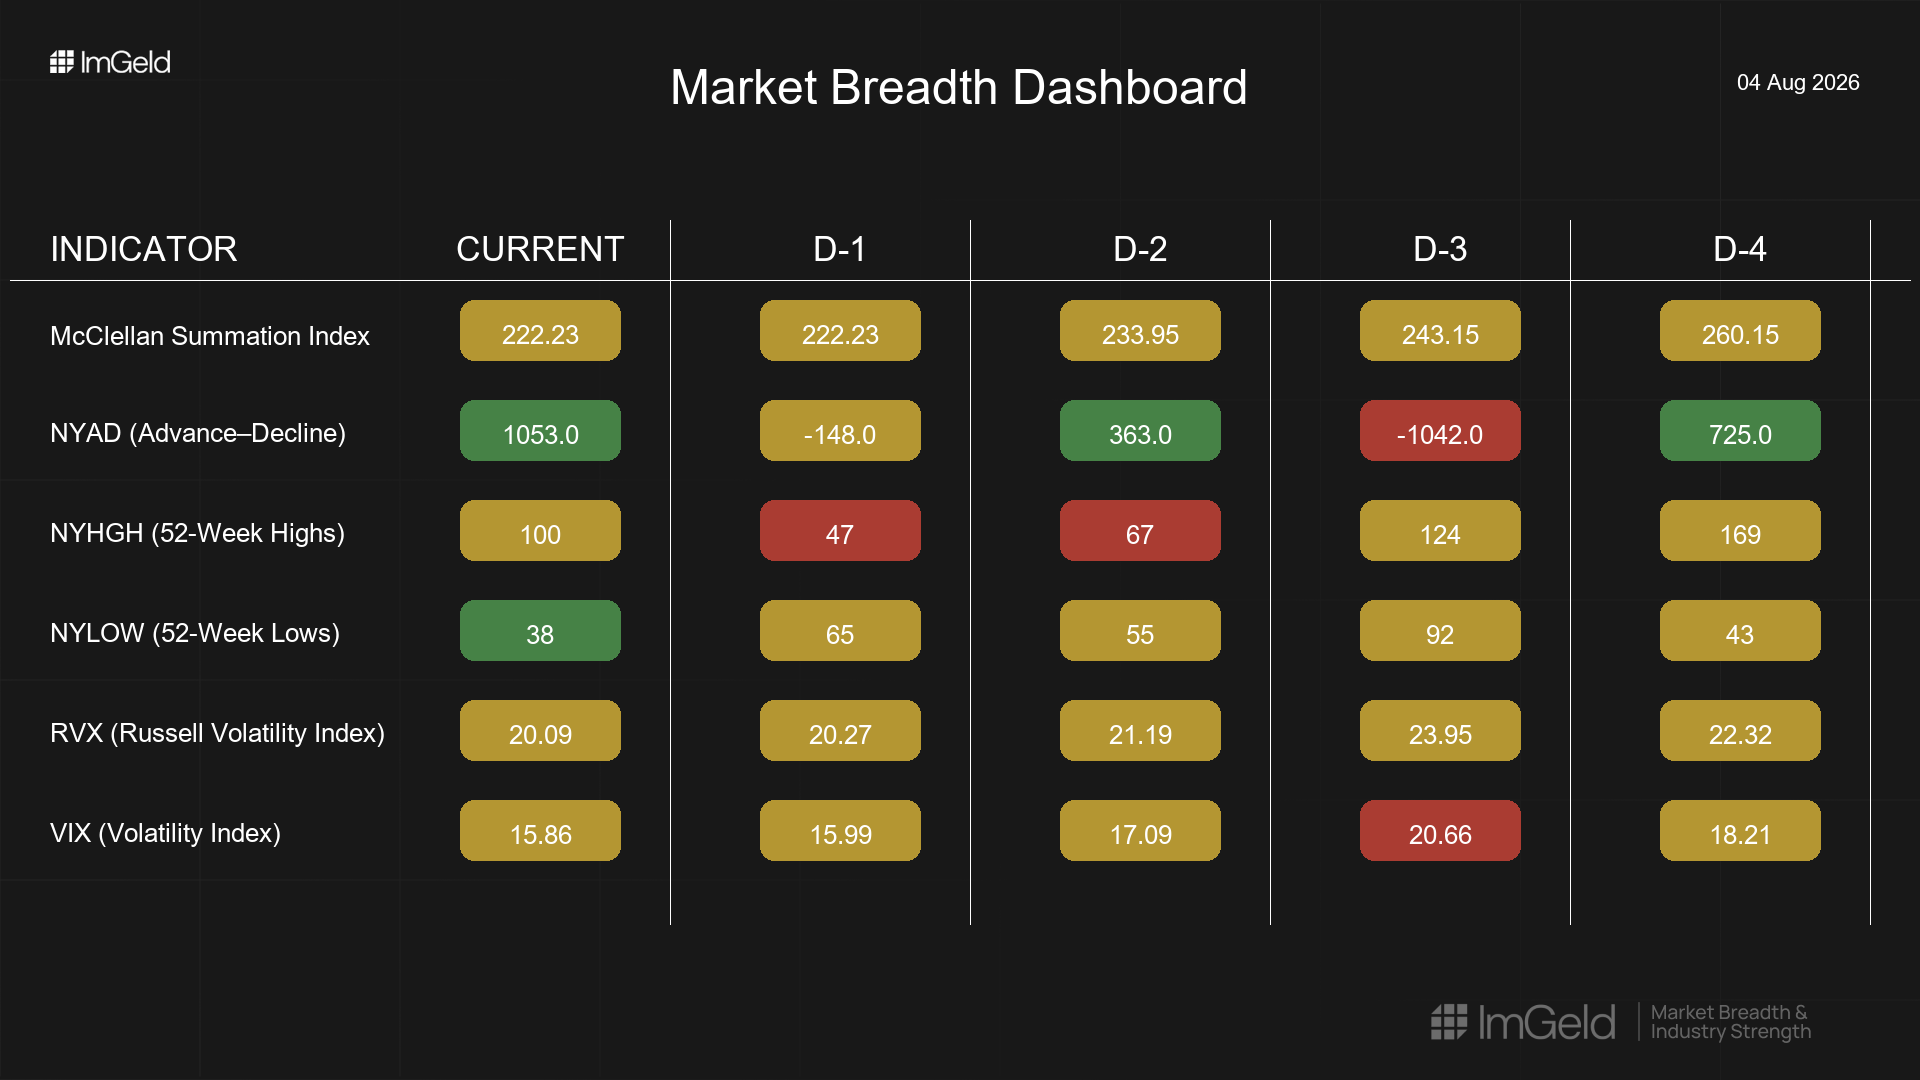
Breadth over the last five sessions shows tentative stabilization. NYSI (McClellan Summation Index) declined from 260.15 to 222.23 and then plateaued, signaling fading intermediate momentum but potential basing. NYAD (Advance-Decline Line) was choppy with outsized dispersion, culminating in a strong positive thrust on 2026-08-03 (1053). Volatility compressed as VIX (CBOE Volatility Index) fell from 20.66 to 15.86 and RVX (Russell Volatility Index) from 23.95 to 20.09, consistent with improving risk appetite.
Tactically, emerging long opportunities favor mid-cap industries showing improving participation and rising new highs, with strict selectivity. Short opportunities remain valid in large-cap, leadership-heavy industries where breadth is narrowing and rallies are being sold.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation narrowed through mid-period and tentatively broadened into the latest session. Leadership, previously concentrated, showed early signs of rotation as NYHGH rebounded and NYLOW eased. Volatility is compressing across large and small universes, supportive of risk-taking if breadth confirmation persists. A mild divergence persists: NYSI is still lower versus the start of the period while NYAD posted a decisive final-day advance. By the five-day consistency rule, the current pattern indicates early accumulation is tentative, pending follow-through.
Indicator Breakdown
NYSI (McClellan Summation Index) The structure declined for four sessions (260.15 to 222.23) and then flattened. This indicates improving downside control but not yet an established upturn. The pause suggests conditions are set for a potential turn if near-term advances persist.
NYAD (Advance-Decline Line) Daily participation was mixed: strong positive (725), sharp negative (-1042), moderate positive (363), slight negative (-148), and strong positive (1053). Net breadth over five days improved but with high day-to-day dispersion, arguing for selective positioning.
NYHGH (New 52-Week Highs) Leadership contracted from 169 to 47, then rebounded to 100. This is an early sign of leadership expansion, but it remains preliminary and requires confirmation via continued upward drift in highs.
NYLOW (New 52-Week Lows) Lows spiked mid-period (92, 65) and fell to 38 in the latest session, indicating easing downside pressure and improving risk appetite.
Volatility Regime VIX compressed from a mid-week spike (20.66) to 15.86, while RVX followed suit to 20.09. The regime shift toward lower implied volatility favors breakout attempts and carry, but failure of breadth to confirm would raise the risk of a quick volatility reversion.
Tactical Implications
Longs: Focus on mid-cap industries with improving breadth and rising highs such as industrial machinery, specialty chemicals, regional banks, and application software. Prioritize names with accelerating participation and low downside volatility.
Shorts: Large-cap industries with narrowing leadership and distribution risk remain candidates, including internet platforms and mega-cap semiconductors, especially on rallies lacking NYAD confirmation.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.