

Executive Summary Date: 2026-09-04
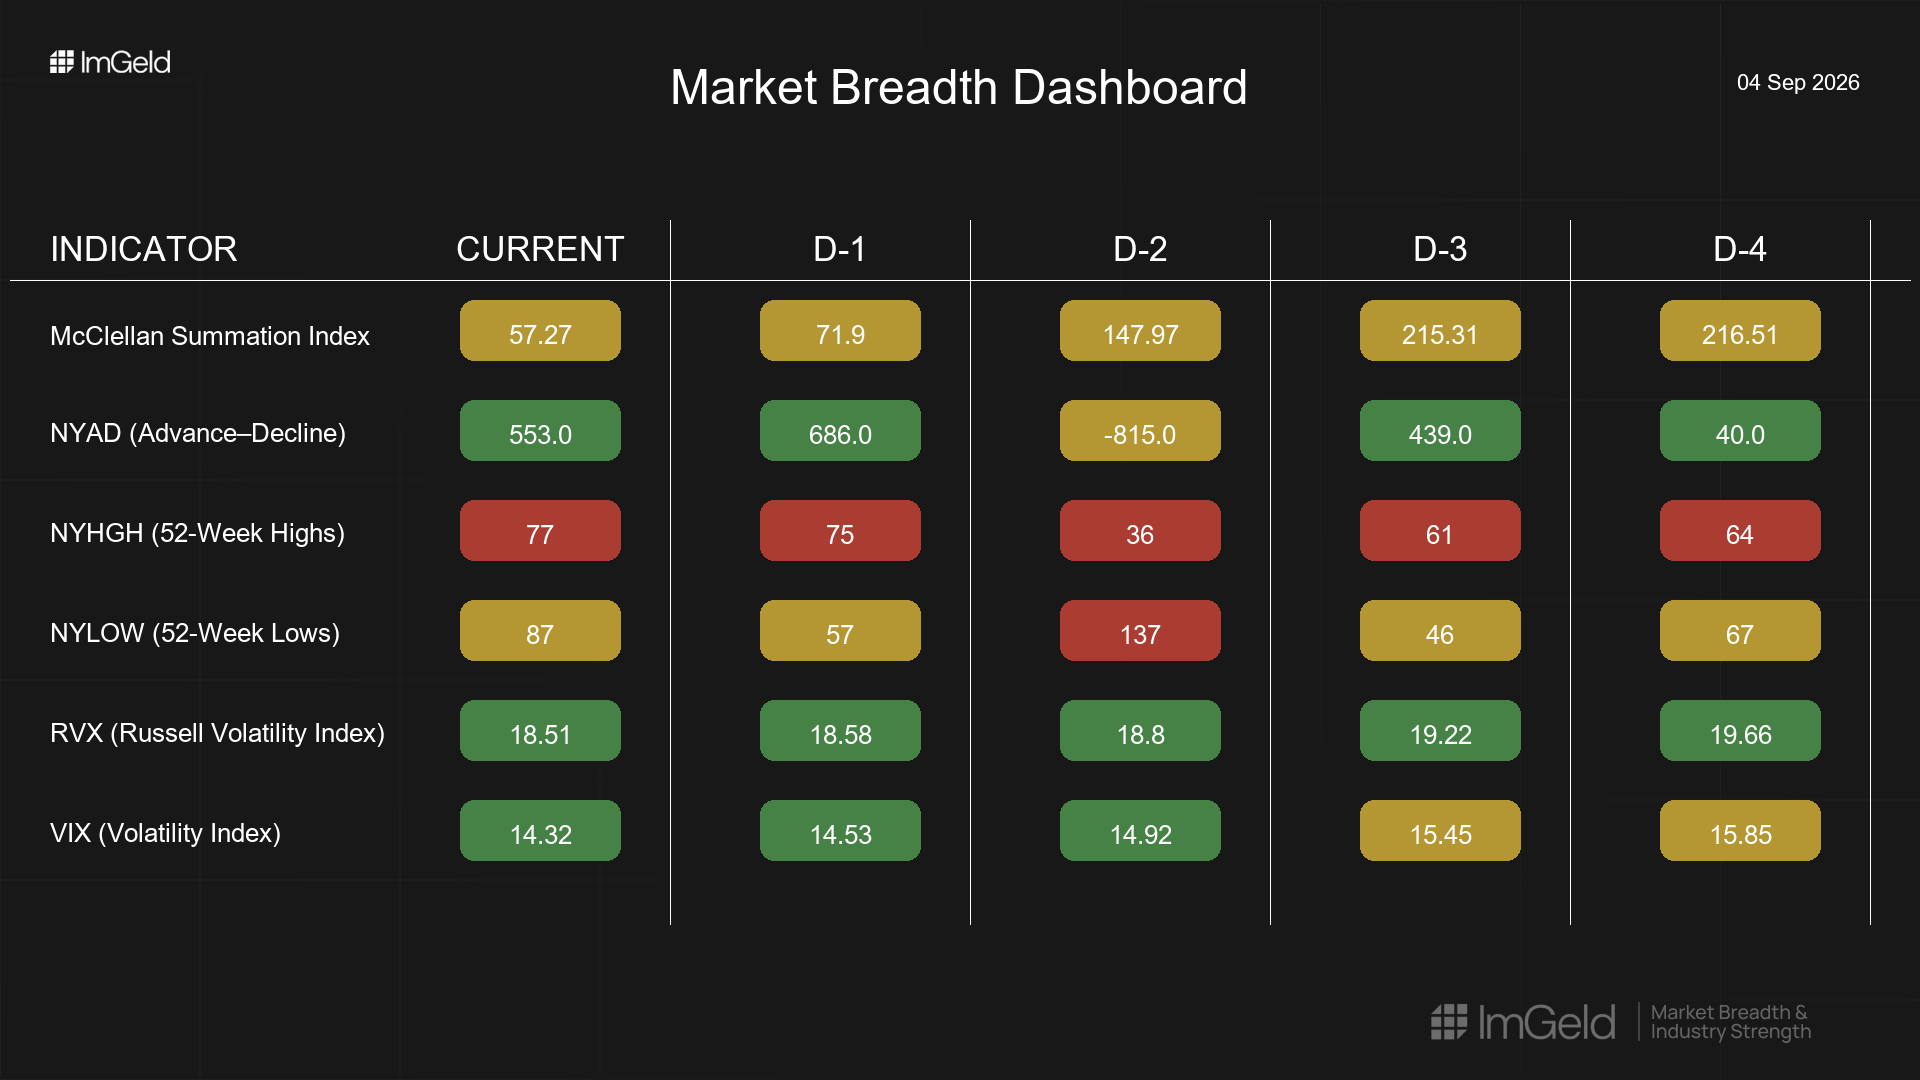
Breadth weakened at the intermediate level while short-term participation improved. NYSI (McClellan Summation Index) fell for five consecutive sessions, signaling a firm deterioration in internal momentum despite staying positive. NYAD (Advance–Decline Line) was net positive over five days with three strong up days, indicating short-term accumulation attempts. VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) compressed steadily, lowering headline risk premium.
Tactically, long opportunities may be emerging selectively in mid-cap industries showing rising new-highs participation and contained new-lows. Short setups remain valid in crowded large-cap leadership where participation is narrowing. Selectivity should remain high.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing at the intermediate trend as NYSI declines firmly, while near-term breadth improved with three strong NYAD advances. Leadership appears more selective rather than broadly rotating, with NYHGH rebounding late week but NYLOW holding above early-week levels. Volatility is firmly compressing across VIX and RVX, supportive of mean reversion but prone to sharp reversals on shocks. There is a clear divergence: a falling NYSI versus improving NYAD. The five-day pattern remains mixed, consistent with an early accumulation attempt within a weakening intermediate backdrop.
Indicator Breakdown
NYSI (McClellan Summation Index) Firmly declining across all five sessions (216.51 to 57.27), indicating deteriorating intermediate momentum despite remaining above zero. A stabilization is needed to confirm any durable advance.
NYAD (Advance–Decline Line) Mixed but net positive: +40, +439, -815, +686, +553. Participation strengthened in the last two sessions, offsetting the mid-week washout. This remains a constructive short-term tone but not yet decisive.
NYHGH (New 52-Week Highs) Leadership expansion turned up late week (64, 61, 36, 75, 77). Two consecutive higher readings render the expansion tentative, not yet broad-based.
NYLOW (New 52-Week Lows) Downside pressure elevated versus early week, with a mid-week spike (67, 46, 137, 57, 87). This remains a caution flag, implying ongoing distribution in laggards.
Volatility Regime VIX compressed steadily from 15.85 to 14.32 and RVX from 19.66 to 18.51, a firmly compressing regime. Lower implied volatility supports tactical rotations and squeezes but can mask fragility; risk controls should assume asymmetry to the upside in volatility.
Tactical Implications
Longs: Focus only on mid-cap industries with improving leadership and controlled lows, such as Industrial Machinery, Specialty Chemicals, Insurance Brokers, and Independent Power Producers. Emphasize relative strength and rising new-highs participation.
Shorts: Large-cap concentrations with narrowing breadth remain vulnerable, particularly in platform software, internet platforms, and semiconductor bellwethers where advances are leadership-driven rather than participatory.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.