

Executive Summary Date: 2026-10-16
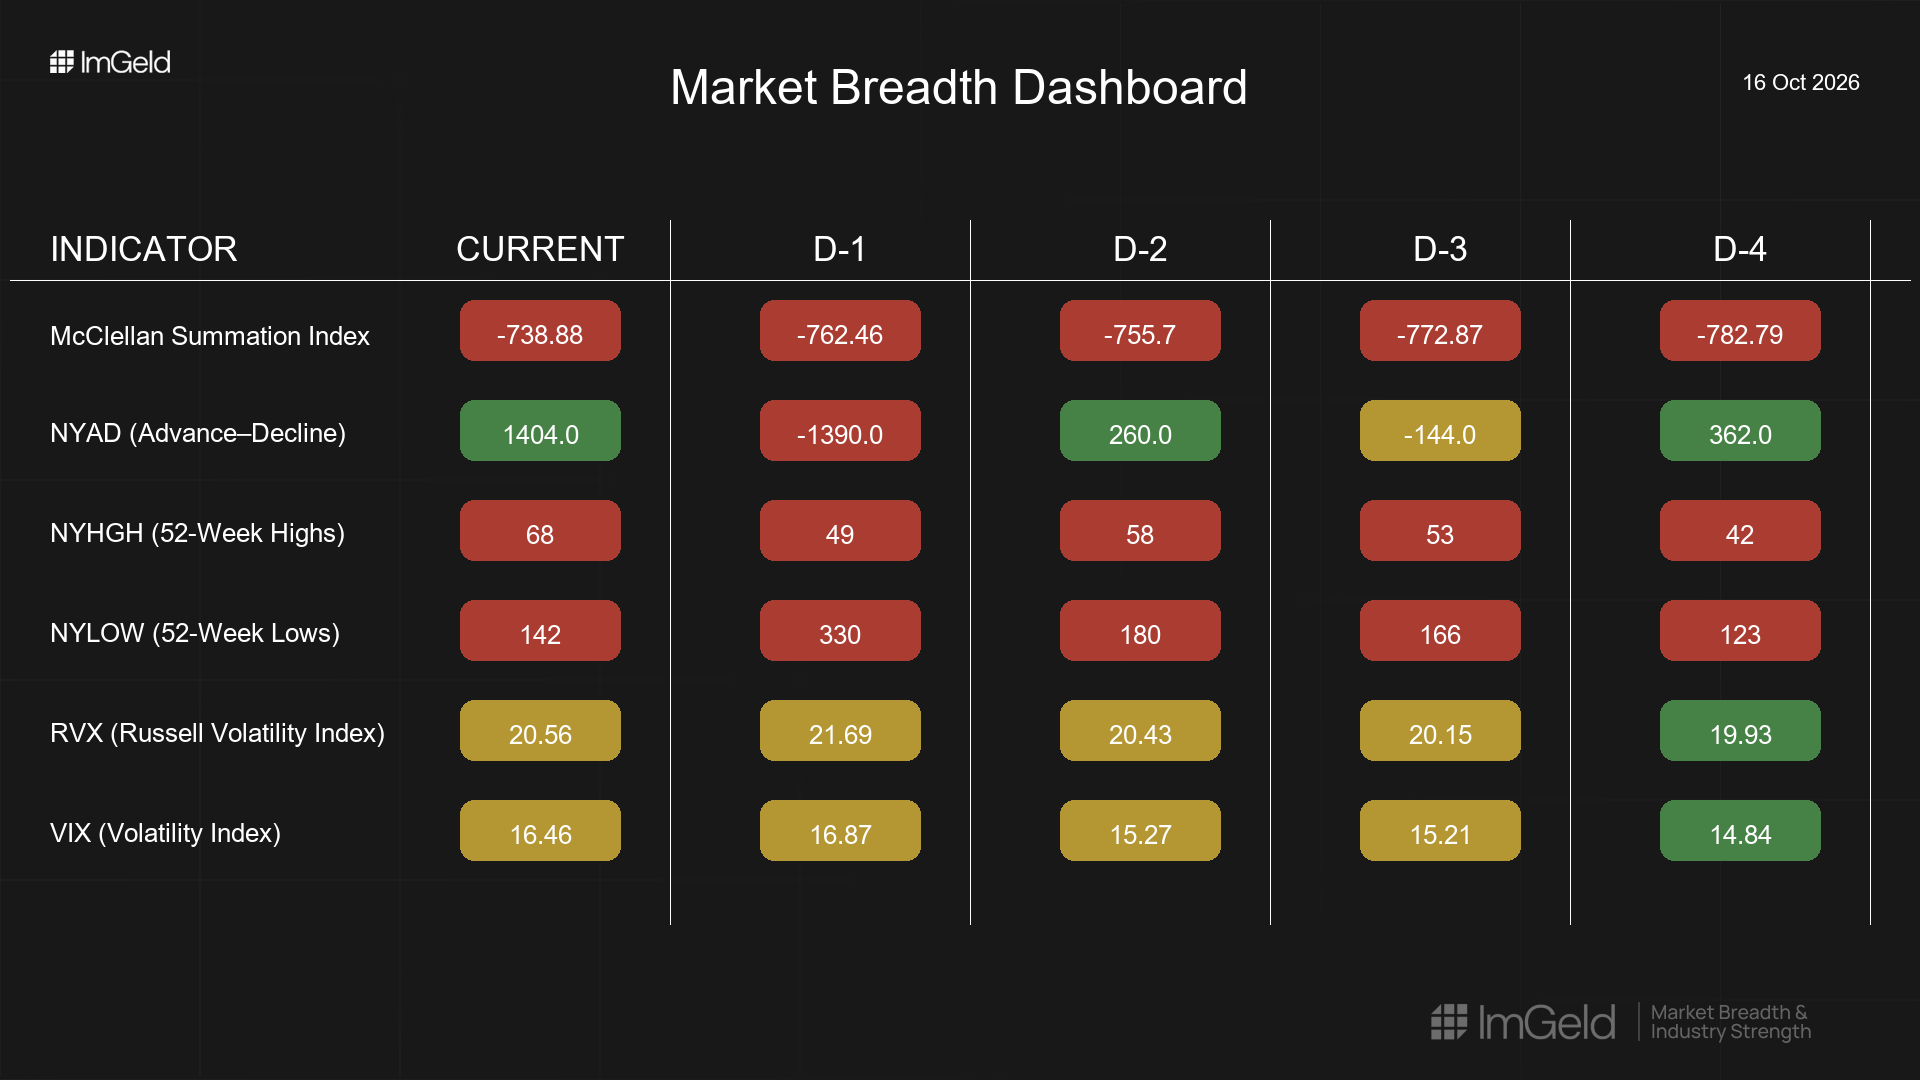
NYSI (McClellan Summation Index) lifted for 4 of the last 5 sessions, improving from deeply negative levels and signaling tentative accumulation.
NYAD (Advance–Decline Line) was choppy with a washout on 10/15 followed by a strong rebound on 10/16, keeping participation mixed.
VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) expanded midweek and eased slightly into today, leaving volatility elevated but contained. Tactically, early long opportunities are emerging in select mid-cap industries where new highs are inching higher and new lows are receding. Short setups remain valid in crowded large caps where leadership is narrowing and volatility is re-pricing. Selectivity remains high.
Get the Industry Heat Map — delivered by email only.
Global Read
Breadth is attempting to broaden as NYSI grinds higher and NYHGH (NYSE New 52-Week Highs) expands modestly, but NYAD’s intraday reversals indicate fragile participation. Leadership appears to be rotating at the margin away from concentration, though evidence is preliminary. Volatility has been expanding, then stabilizing into a higher, more neutral regime. There is a mild positive divergence with NYSI improving while NYAD remains inconsistent. By the five-day consistency rule: NYSI is firmly improving, NYAD remains mixed, and the aggregate pattern suggests early accumulation, still tentative.
Indicator Breakdown
NYSI (McClellan Summation Index)
Direction: Improving. Four advances and one minor setback, moving from -782.8 to -738.9. Still below zero, so the upturn is fragile and requires follow-through.
NYAD (Advance–Decline Line)
Participation: Mixed and volatile. Daily prints of +362, -144, +260, -1390, +1404 net to a gain but reflect inconsistent buying pressure.
NYHGH (NYSE New 52-Week Highs)
Leadership: Gradual expansion (42 → 68). A constructive step, but absolute levels remain modest and need further build to confirm sustainable leadership.
NYLOW (NYSE New 52-Week Lows)
Downside Pressure: Spiked midweek (330) before easing to 142. Risk appetite is stabilizing, but lows remain elevated versus highs; damage has not fully cleared.
Volatility Regime
VIX rose from 14.8 to 16.9 before slipping to 16.5; RVX from 19.9 to 21.7 before easing to 20.6. This reflects a shift from complacent to neutral-vol terrain. Tactical entries should be staggered; maintain hedges given headline sensitivity.
Tactical View
Long: Focus selectively on mid-cap industries showing improving breadth and relative strength, such as capital goods suppliers, aerospace and defense components, specialty chemicals, niche software, and healthcare equipment, where new highs are firming and lows are contained.
Short: Large-cap leadership that is overcrowded and deteriorating on breadth remains susceptible, particularly where earnings dispersion and higher volatility are pressuring multiples.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.