

Executive Summary Date: 2026-09-28
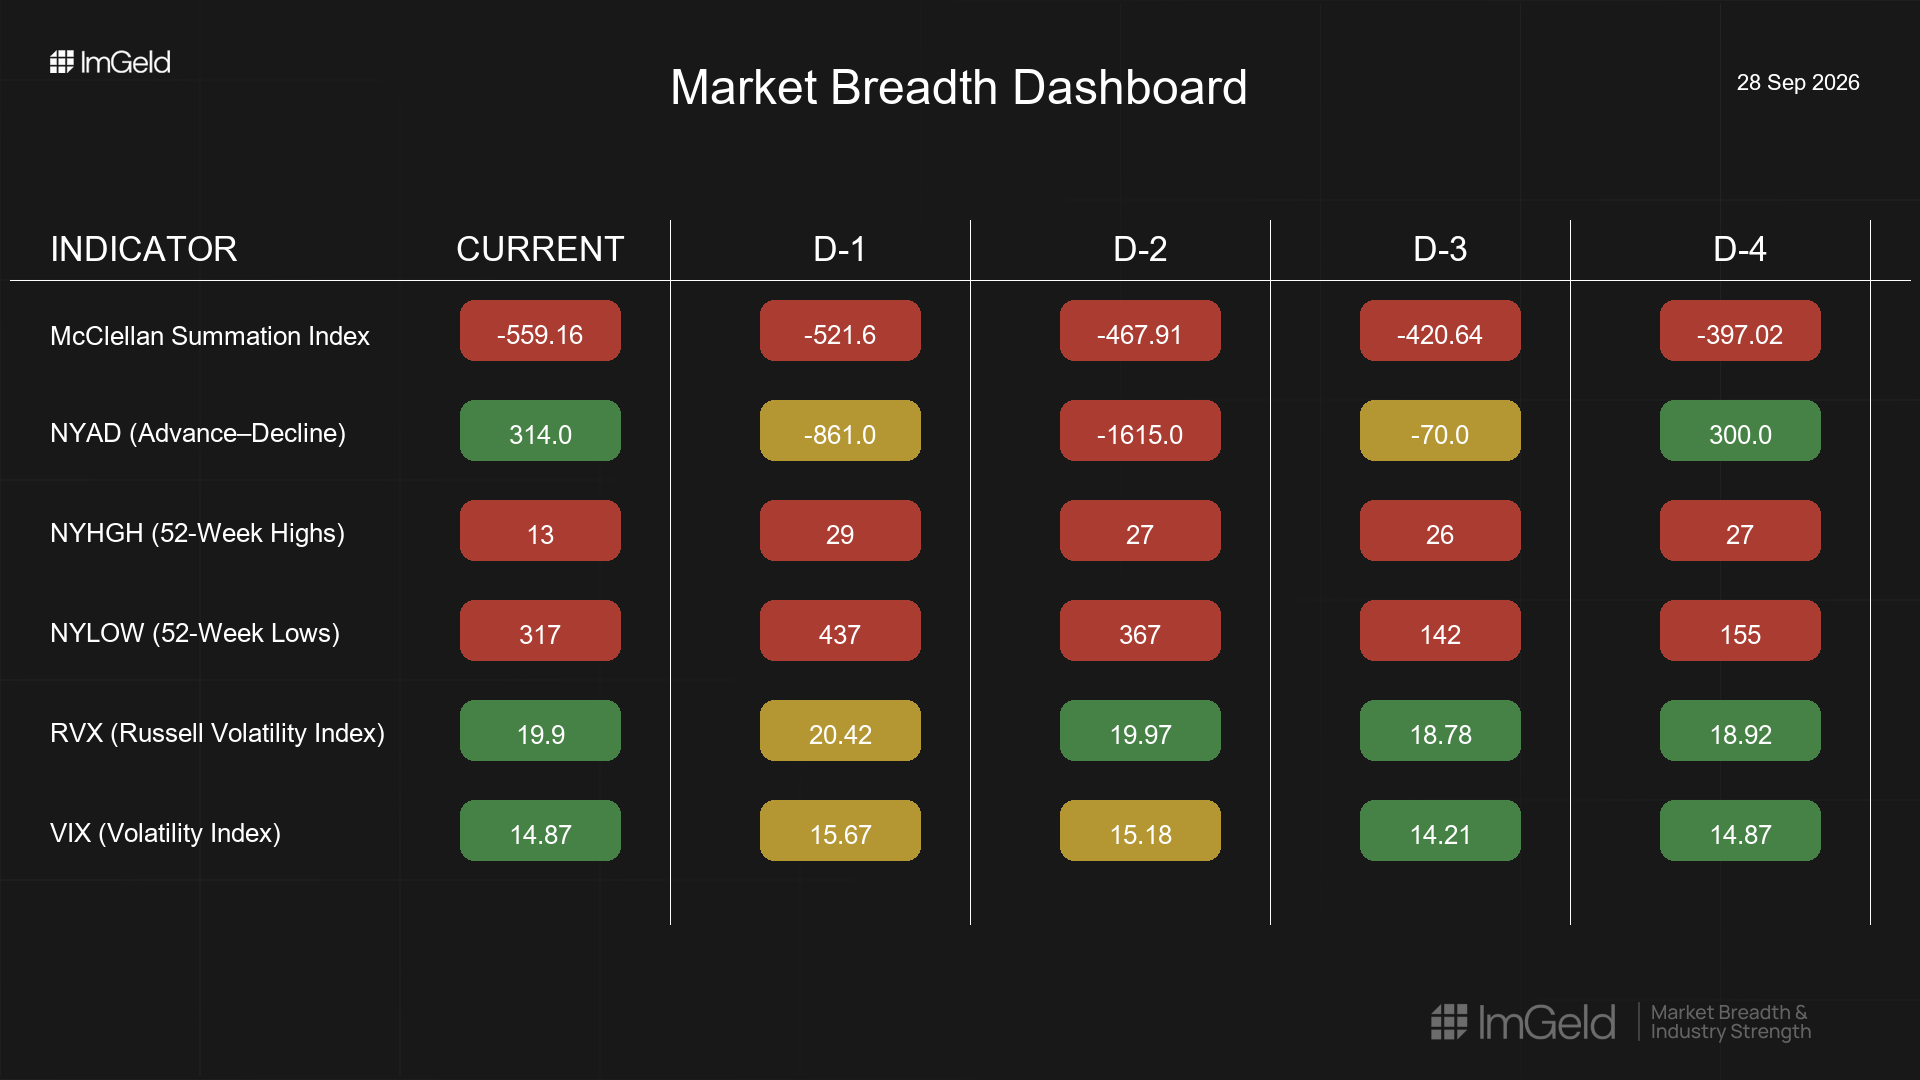
Bias: Tentative short. Over the last five sessions, NYSI (McClellan Summation Index) declined steadily to deeper negatives, confirming deteriorating internal momentum. NYAD (Advance–Decline Line) was volatile, with two sharp down days bookended by modest positives, signaling fragile participation. VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) rose mid-week then eased, keeping volatility contained relative to breadth stress. Tactically, selective mid-cap long setups may emerge in defensive, cash-generative industries showing relative strength, while short opportunities remain valid in large-cap high-beta and late-cycle cyclical industries. Selectivity remains high.
Get the Industry Heat Map — delivered by email only.
Global Read
Breadth has narrowed firmly over five days as new highs contracted and new lows stayed elevated. Leadership is becoming more concentrated rather than rotating broadly. Volatility briefly expanded then recompressed, leaving room for squeezes without confirming a trend reversal. A divergence persists, with NYAD recovering today while NYSI continues to fall, implying bounces lack internal thrust. By the five-day consistency rule, the pattern indicates continuation of deterioration; isolated positives are Tentative only.
Indicator Breakdown
NYSI (McClellan Summation Index) Five consecutive declines from -397.02 to -559.16. Structure is firmly weakening, below zero and accelerating, consistent with ongoing distribution.
NYAD (Advance–Decline Line) Readings of +300, -70, -1,615, -861, +314. Participation remains weak; the two large negative days dominate the tape. Today’s positive breadth is isolated and not yet signaling accumulation.
NYHGH (New 52-Week Highs) 27, 26, 27, 29, 13. Leadership expansion contracted sharply on the final session, indicating fewer breakouts and narrowing leadership.
NYLOW (New 52-Week Lows) 155, 142, 367, 437, 317. Downside pressure is elevated despite a modest pullback from the peak, pointing to persistent risk aversion and sectoral stress clusters.
Volatility Regime VIX (CBOE Volatility Index): 14.87, 14.21, 15.18, 15.67, 14.87. RVX (Russell Volatility Index): 18.92, 18.78, 19.97, 20.42, 19.90. Brief mid-week expansion followed by re-compression. Low absolute levels versus breadth stress favor selling rips tactically on the short side, while any long risk should be highly selective and skewed to mid-cap defensive industries.
Tactical Takeaway
Longs: Focus only on mid-cap names within defensively positioned industries such as utilities, waste and environmental services, and select healthcare services where relative strength and stability persist.
Shorts: Large-cap high-beta and cyclical industries with deteriorating breadth and clustering new lows remain actionable into strength.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.