

Executive Summary Date: 2026-10-28
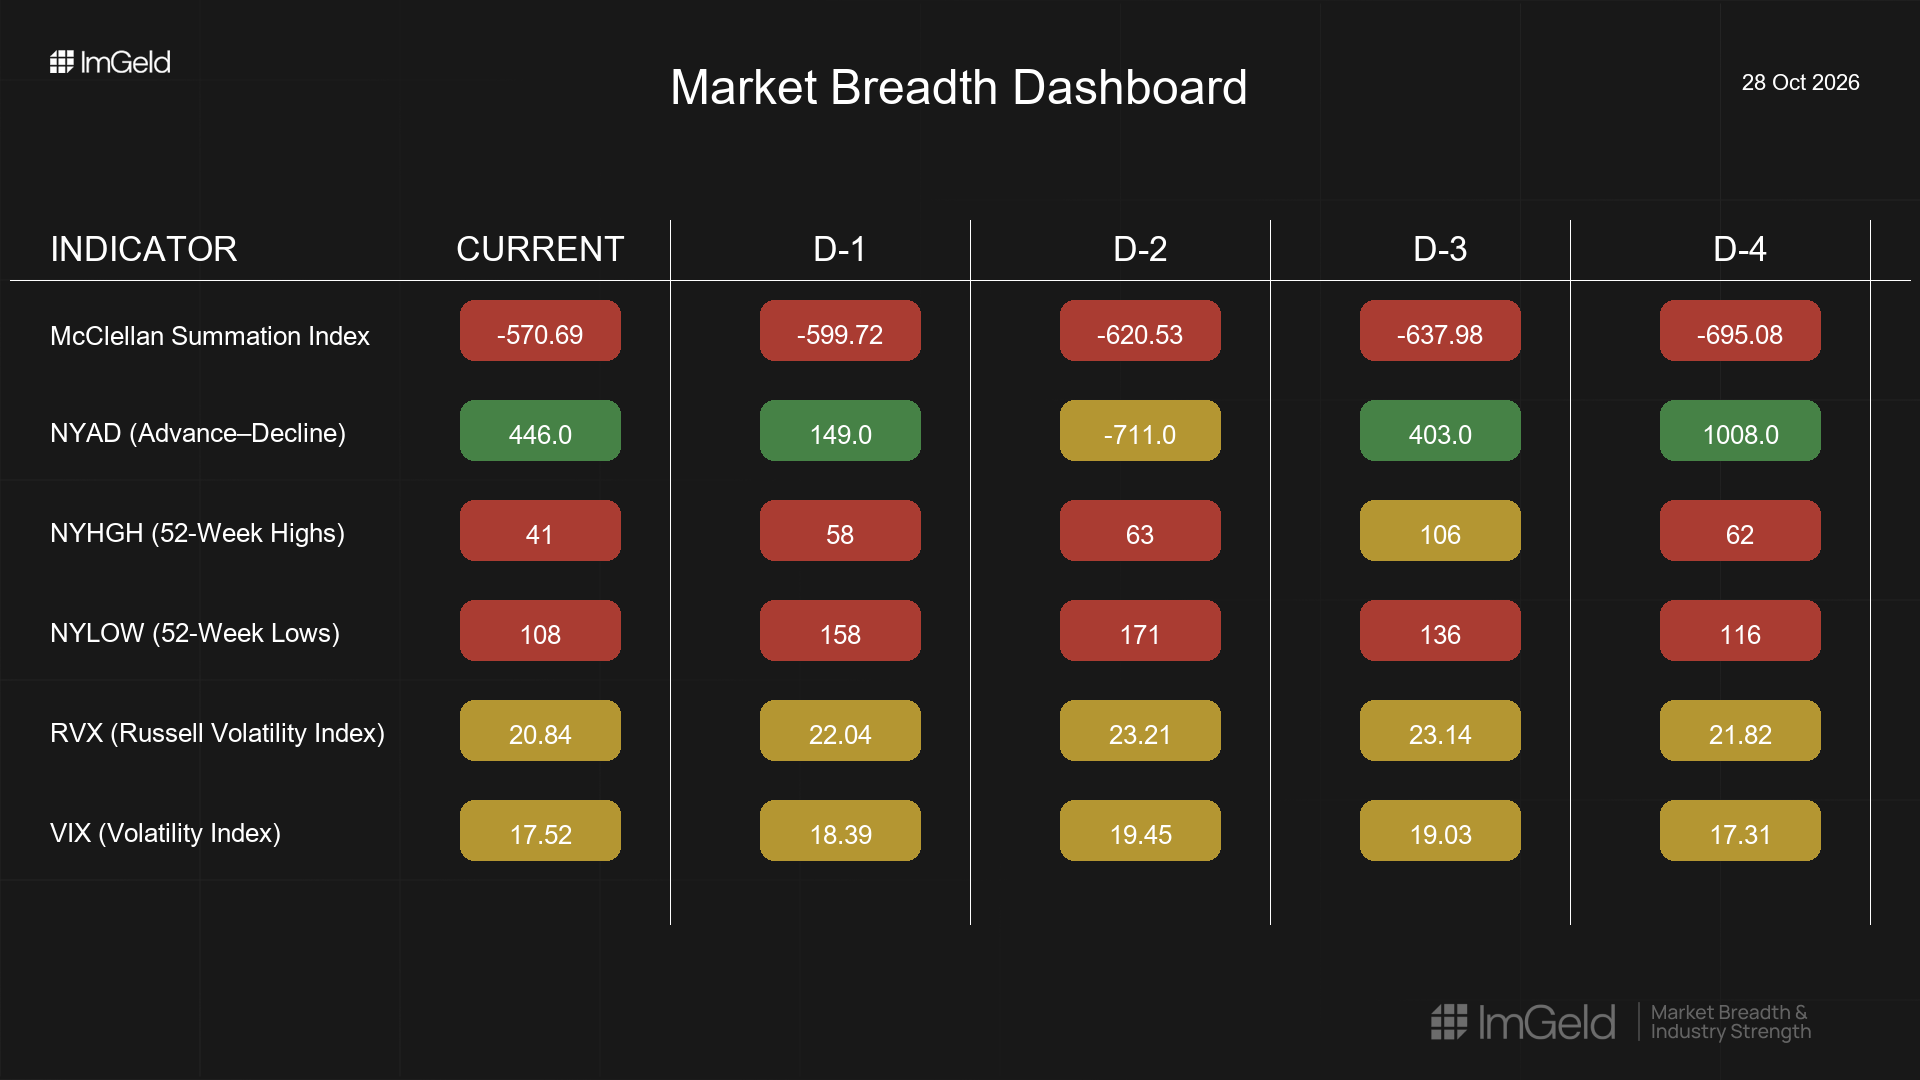
Breadth improved off deeply negative levels while leadership narrowed. NYSI (McClellan Summation Index) rose for five consecutive sessions from -695 to -571, indicating a firming internal thrust despite remaining below zero. NYAD (Advance–Decline Line) was net positive over the period but choppy, with one sharp down day offset by three up days. Volatility eased as VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) retreated from mid-period highs, reflecting tentative compression.
Tactically, selective long opportunities may be emerging in mid-cap industries displaying improving advance–decline participation and resilient lows. Short setups remain valid in crowded large caps where leadership is narrowing and breakouts are failing. Selectivity remains high.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is attempting to broaden beneath the surface as shown by the persistent NYSI improvement and net-positive NYAD, yet leadership is becoming more concentrated with NYHGH declining across the week and NYLOW only modestly retreating. Volatility is compressing into the close of the period, consistent with stabilization rather than a full risk-on pivot. A mild divergence is present: NYSI firmed steadily while NYAD was uneven and new highs contracted, suggesting accumulation is early and not yet confirmed by leadership expansion. By the five-day consistency rule: NYSI is firmly improving, NYAD remains mixed, and volatility is tentatively compressing. The pattern signals early accumulation with incomplete confirmation.
Indicator Breakdown
NYSI (McClellan Summation Index) Improving consistently over five sessions, reducing the depth of negative readings. Structure is healing but still sub-zero, consistent with an early-stage breadth repair rather than a completed reversal.
NYAD (Advance–Decline Line) Day-to-day participation was uneven: strong positive starts, a sharp setback mid-period, then two constructive days. Breadth is strengthening at the margin but remains fragile.
NYHGH (New 52-Week Highs) Contracted from 106 to 41, indicating narrowing leadership and limited follow-through on rallies. Breakout quality is poor.
NYLOW (New 52-Week Lows) Eased from 171 to 108 into the period’s end. Downside pressure is abating but remains elevated, keeping risk appetite constrained.
Volatility Regime VIX moved from 19.45 down to 17.52; RVX from 23.21 to 20.84. Both indicate compression, supportive of mean reversion and stock selection. The RVX–VIX relationship remains orderly, favoring relative-value positioning over beta exposure.
Tactical Implications
Longs: Focus on mid-cap industries (3–10B) where up-day breadth and relative strength are improving, such as industrial machinery, building products, specialty insurance, and select regional banks with declining new lows and rising up-volume.
Shorts: Over-owned large caps in internet and semiconductor industries remain vulnerable as leadership narrows and new highs deteriorate; fade strength into known supply.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.