

Executive Summary Date: 2026-10-23
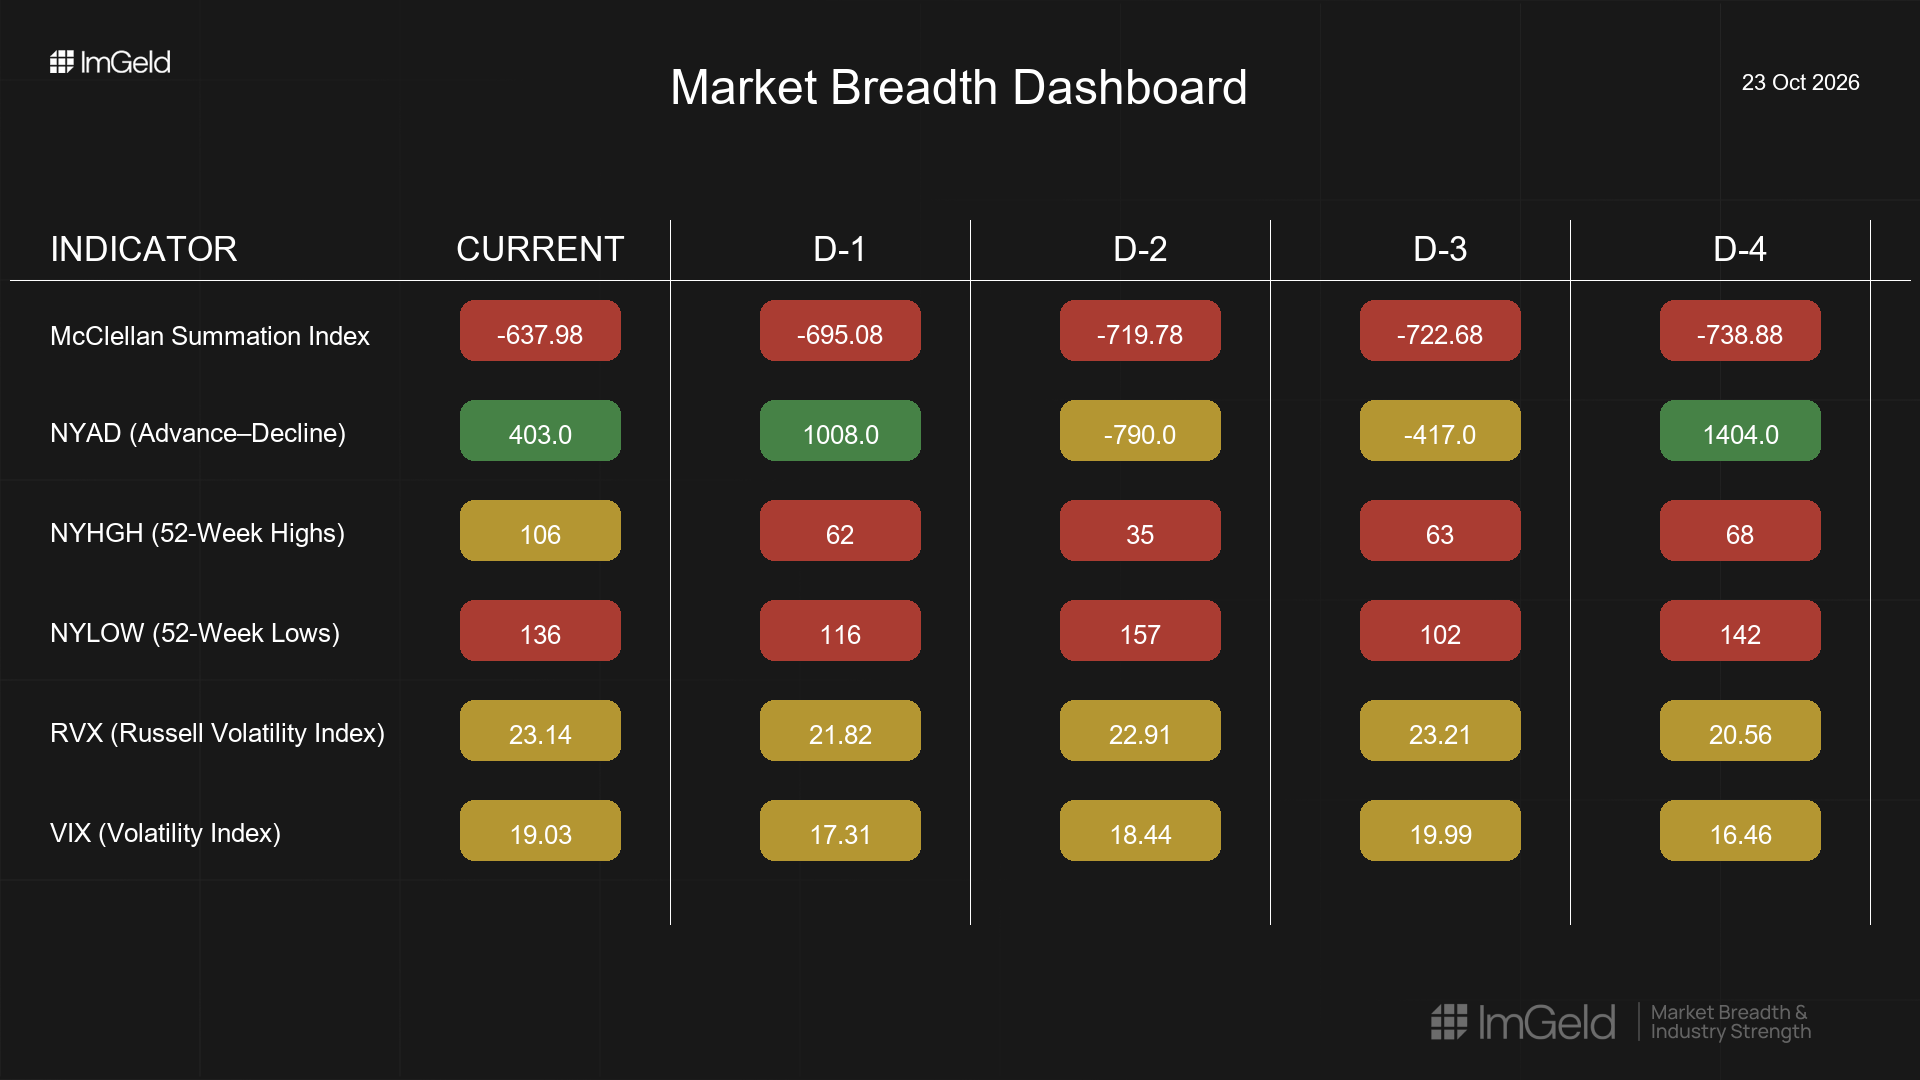
Breadth has improved modestly over the last five sessions. The NYSI (McClellan Summation Index) rose steadily but remains deeply negative, signaling an early repair phase. The NYAD (Advance–Decline Line) was volatile but finished with two consecutive positive readings, indicating tentative follow-through. The VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) firmed into week’s end, keeping risk premia elevated. Tactically, early long opportunities may be emerging in select mid-cap industries where new highs are expanding and pullbacks are being bought, while short setups remain valid in crowded large-cap leadership where participation is thinning. Selectivity is paramount.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is tentatively broadening: new highs expanded while the NYSI climbed each day, though still below zero. Leadership shows early rotation away from mega-cap concentration toward more diversified mid-cap groups, but confirmation is pending. Volatility expanded late week, arguing for staggered entries and disciplined risk controls. There is a constructive divergence with NYSI improving from depressed levels while NYAD remains choppy; this often marks early accumulation rather than a mature up-leg. Given mixed signals within the five-day window, the regime remains tentative per the five-day consistency rule.
Indicator Breakdown
NYSI (McClellan Summation Index) Improving: -738.88 to -637.98 across five sessions. The persistent rise indicates breadth repair, but the still-negative level underscores incomplete trend reversal and vulnerability to volatility spikes.
NYAD (Advance–Decline Line) Mixed but stabilizing: +1404, -417, -790, +1008, +403. After midweek deterioration, participation strengthened into the close of the period, consistent with tentative accumulation.
NYHGH (New 52-Week Highs) Leadership expansion: 68, 63, 35, 62, 106. The surge to triple digits suggests nascent leadership breadth, led by selective mid-cap industries.
NYLOW (New 52-Week Lows) Downside pressure remains elevated: 142, 102, 157, 116, 136. Persistent triple-digit lows imply ongoing dispersion; avoid laggards with deteriorating internals.
Volatility Regime VIX rose from 16.46 to 19.03 and RVX from 20.56 to 23.14. The late-week expansion favors maintaining hedges, fading overstretched bounces, and emphasizing risk management over outright aggression.
Tactical Take
Longs: Focus on mid-cap industries showing relative strength and improving breadth (e.g., select industrial suppliers, life science tools, specialty materials). Stagger entries and demand confirmation via sustained advances in new highs.
Shorts: Large-cap leadership with narrowing participation and crowding risk remains vulnerable on rallies (e.g., platform technology and other mega-cap growth-heavy industries). Use strength to initiate or add with defined risk.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.