

Executive Summary Date: 2026-09-21
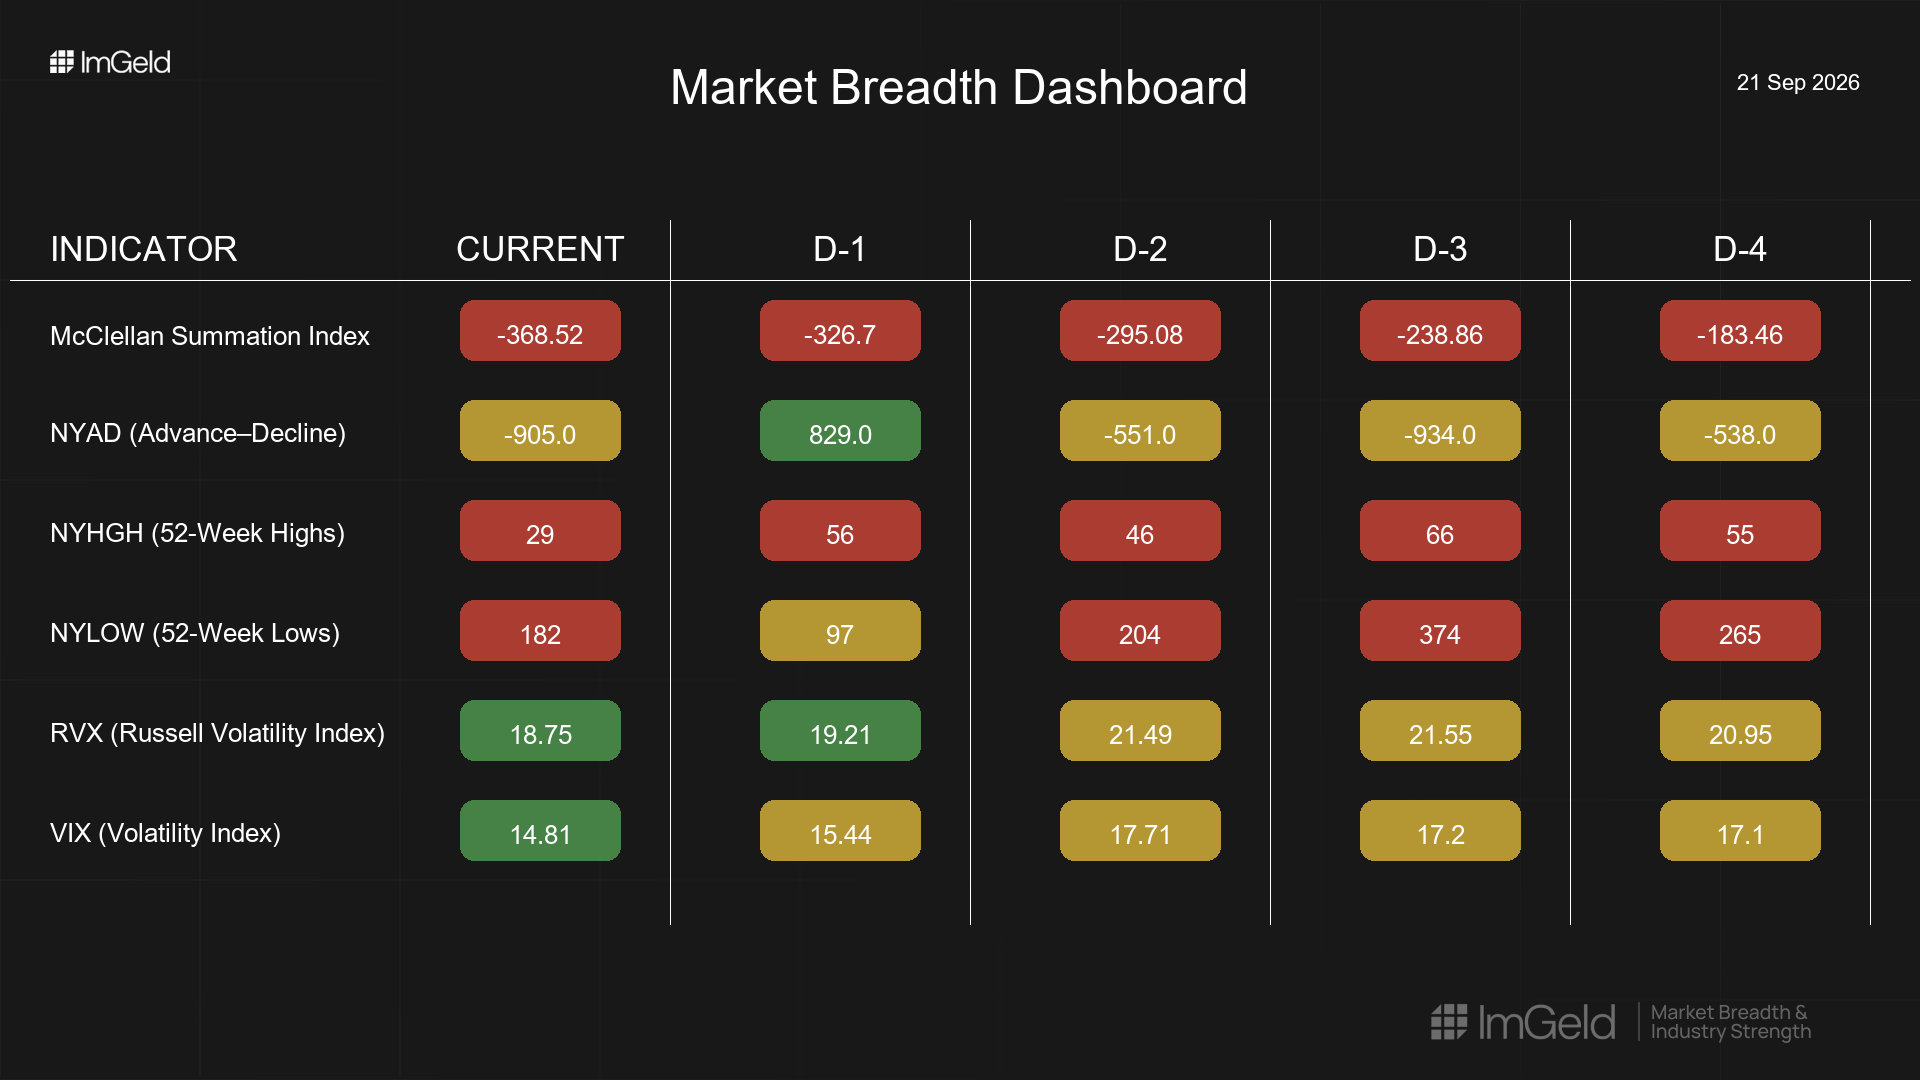
Breadth deteriorated over the last five sessions: NYSI (McClellan Summation Index) fell steadily deeper into negative territory, NYAD (Advance–Decline Line) printed four negative days out of five, NYHGH (New 52-Week Highs) contracted, and NYLOW (New 52-Week Lows) remained elevated. Volatility compressed as VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) trended lower, signaling complacency despite weakening participation. Tactically, any long exposure should be highly selective and limited to mid-cap industries showing persistent relative strength and stable earnings quality. Short setups remain valid, particularly in large-cap growth and cyclical industries where leadership is narrowing. Selectivity is high; prefer strength-to-fade rather than chasing weakness
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing, with leadership becoming more concentrated as NYHGH declined and NYLOW stayed comparatively high. Volatility compressed firmly across the week (VIX and RVX down), increasing the risk of abrupt repricing if volatility re-expands. A brief NYAD positive spike on 09-18 diverged from the persistently declining NYSI, indicating a counter-trend rally lacking follow-through. Applying the five-day consistency rule: NYSI is firmly deteriorating; NYAD is firmly weak with one isolated improvement; volatility is firmly compressing. The five-day pattern signals continuation of distribution rather than early accumulation; exhaustion is more likely in laggards than leaders.
Indicator Breakdown
NYSI (McClellan Summation Index) Declined each session from -183 to -369, confirming a firmly weakening structure and negative momentum in aggregate breadth.
NYAD (Advance–Decline Line) Net negative on 09-15, 09-16, 09-17, and 09-21, with one strong positive day on 09-18 that failed to shift the trend. Daily participation is weakening and rallies are not broadly supported.
NYHGH (New 52-Week Highs) Fell from mid-60s to 29, indicating leadership expansion is fading; upside breakouts are scarce and increasingly concentrated.
NYLOW (New 52-Week Lows) Persistently elevated (peak 374; latest 182). A brief easing on 09-18 reversed, underscoring ongoing downside pressure and fragile risk appetite.
Volatility Regime VIX slid from 17.7 to 14.8; RVX from 21.5 to 18.8. Firm compression amid weakening breadth suggests complacency risk. Expect choppy rallies with vulnerability to sharp drawdowns upon volatility re-expansion; timing entries on strength remains preferable for short positioning.
Tactical Implications
Longs: Only highly selective mid-cap industries with defensiveness and improving relative strength (e.g., power producers within utilities value-chain, specialty insurers, niche medical devices). Patience and tight risk controls required.
Shorts: Remain valid in large-cap growth and cyclical industries where breadth is deteriorating and leadership is narrowing (e.g., semiconductors, internet retail, machinery). Favor selling strength into failed breakouts or lower-high setups.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.