

Executive Summary Date: 2026-10-23
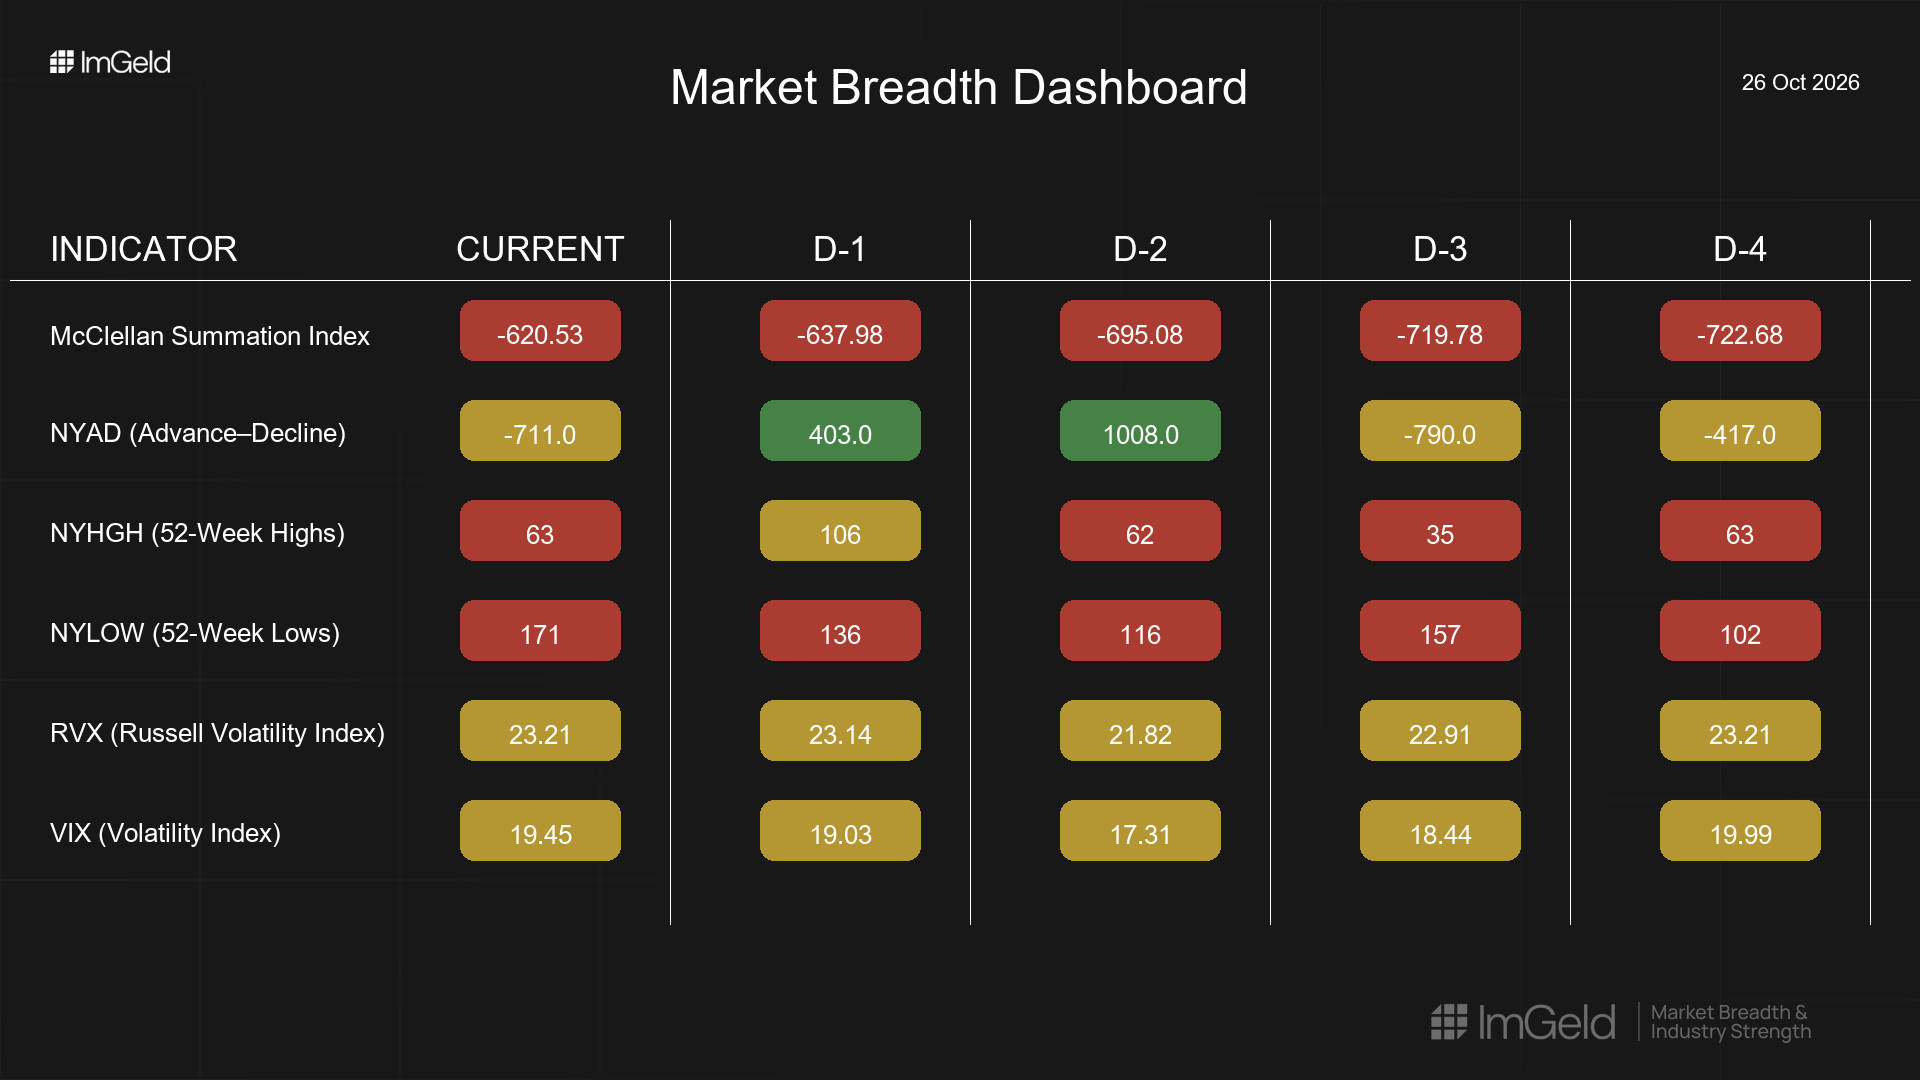
Breadth is attempting to stabilize but remains fragile. NYSI (McClellan Summation Index) rose steadily across the last five sessions, yet remains deeply negative. NYAD (Advance-Decline Line) was net negative over the window, with a sharp deterioration on 10/26. VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) re-expanded into the period end. Tactical stance: tentative short bias. Short setups remain valid, especially in large-cap leadership clusters within Software, Semiconductors, and Internet-related industries. Any long exploration should be highly selective and limited to mid-cap industries showing relative strength and low new-lows intensity; confirmation is not in place.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing as new lows expanded while new highs faded after a brief uptick. Leadership remains concentrated, with no durable expansion in highs. Volatility shifted from midweek compression to renewed expansion, indicating fragile risk appetite. There is a divergence: NYSI improved consistently, while NYAD turned negative on the latest day, suggesting internal thrust without broad daily participation. Applying the five-day consistency rule: NYSI improvement is firmly in place; NYAD and highs-lows remain mixed; volatility has been firmly re-expanding over the last two sessions. The pattern signals an early accumulation attempt that is not confirmed, with continuation risk to the downside.
Indicator Breakdown
NYSI (McClellan Summation Index) Improving for five consecutive readings, from -722.68 to -620.53. The structure is better but still subzero, consistent with a tentative inflection within a bearish backdrop.
NYAD (Advance-Decline Line) Choppy and net negative over five days (-507 cumulative), with negative days on 10/19, 10/20, and 10/26. Participation is weakening on balance.
NYHGH (New 52-Week Highs) Oscillated from 63 to 106 back to 63. Leadership expansion is not sustained, indicating narrow winners.
NYLOW (New 52-Week Lows) Rose into 171 on 10/26. Downside pressure is building, and risk appetite remains constrained.
Volatility Regime VIX fell to 17.31 midweek then rebounded to 19.45; RVX mirrored from 21.82 to 23.21. This re-expansion supports maintaining a cautious tape view, favoring opportunistic shorts into strength and patience on unconfirmed longs.
Tactical Considerations
Short side: Large-cap leadership remains vulnerable across Software, Semiconductors, and Internet & Media industries where positioning is crowded and reversals can extend.
Long side: Only consider watchlists in mid-cap groups with improving relative strength and stable internals, such as select Specialty Chemicals, Insurance Brokers, and Infrastructure Services. Execution should wait for confirmation via sustained NYAD improvement and contraction in new lows
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.