

Executive Summary Date: 2026-10-30
Bias: Tentative short. Over the last five sessions, NYSI (McClellan Summation Index) improved from deeply negative levels though remains below zero, while NYAD (Advance-Decline Line) whipsawed and finished with a strong positive breadth day. VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) compressed for four sessions, then ticked higher into the close of the week. Tactically, selective mid-cap long set-ups may be emerging in industries showing improving participation and declining new lows, while short opportunities remain valid in concentrated large-cap leadership where breadth is still narrow. High selectivity is required.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is modestly broadening, evidenced by rising NYSI and a powerful NYAD finish, yet leadership remains concentrated because new 52-week highs did not expand meaningfully. Volatility compressed, then re-bid slightly, consistent with bear-market rally dynamics rather than a full risk-on pivot. There is a constructive divergence with NYSI improving despite mixed NYAD prints. The five-day pattern signals early accumulation but only tentative, given the lack of sustained highs expansion and residual downside pressure earlier in the week. By the five-day consistency rule: participation remains mixed, volatility was firmly compressing then paused, and the accumulation signal is tentative.
Indicator Breakdown
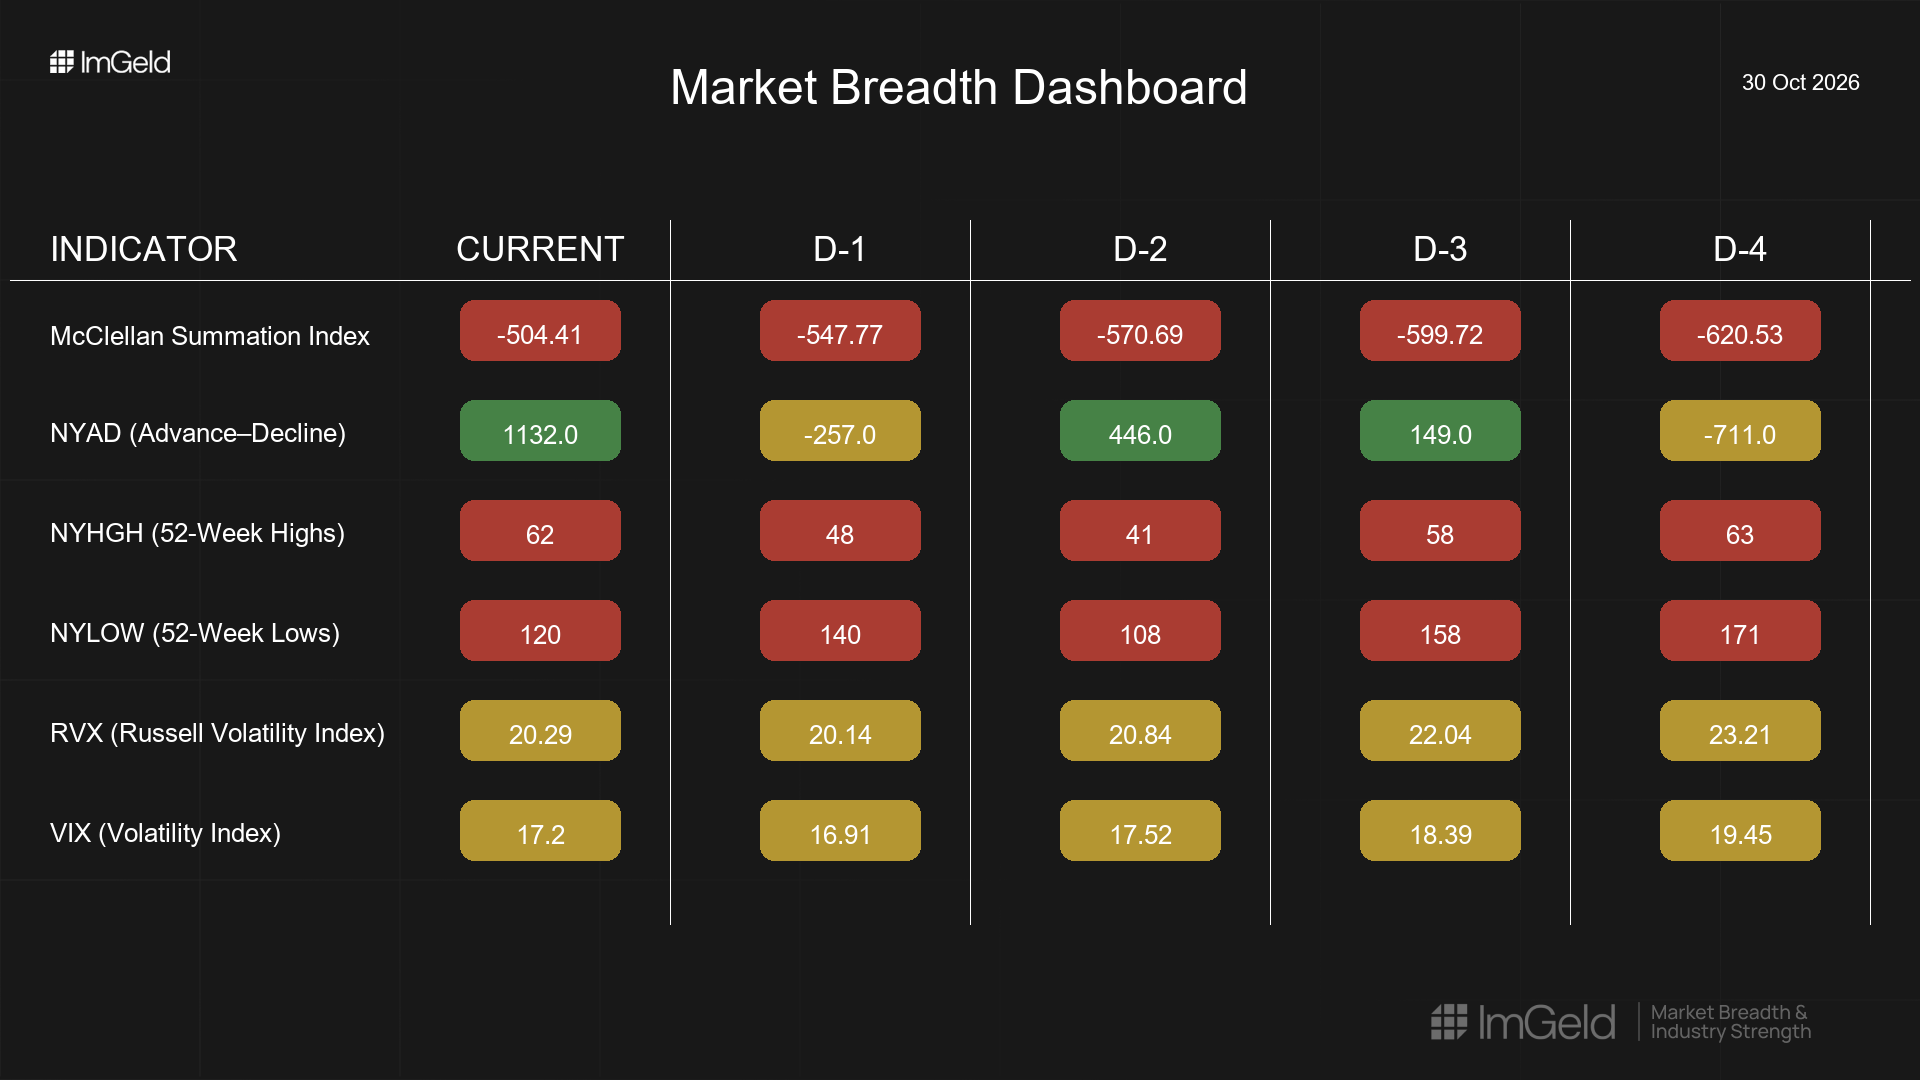
NYSI (McClellan Summation Index) Structure is improving steadily, moving from -620.53 to -504.41 over five days. It remains below zero, so the primary downtrend persists, but downside momentum is fading.
NYAD (Advance-Decline Line) Daily participation was mixed: -711, +149, +446, -257, +1132. The strong finish points to improving breadth, but the lack of multi-day consistency keeps the signal in the “remains mixed” bucket.
NYHGH (New 52-Week Highs) Muted and non-accelerating, hovering in the 40 to low-60s range. Leadership expansion is tentative, not broad. This argues for tight risk management on any longs.
NYLOW (New 52-Week Lows) Trending lower overall from 171 to 120, with one mid-week uptick. Downside pressure is firmly easing, an early sign of risk appetite returning beneath the surface.
Volatility Regime VIX fell from 19.45 to 16.91 before edging up to 17.20; RVX mirrored this from 23.21 to 20.14 then to 20.29. Four days of compression followed by a modest re-bid support a tactical fade-the-rip framework and disciplined position sizing.
Tactical Take
Mid-cap longs: prioritize industries showing improving breadth and declining new lows such as industrial machinery, building products, specialty retail, application software, and semiconductor equipment. Execution should be staged.
Shorts: remain valid in large-cap dominated industries with crowded leadership and weak highs expansion, including interactive media and services, large-cap semiconductors, and integrated energy.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.