

Executive Summary Date: 2026-09-11
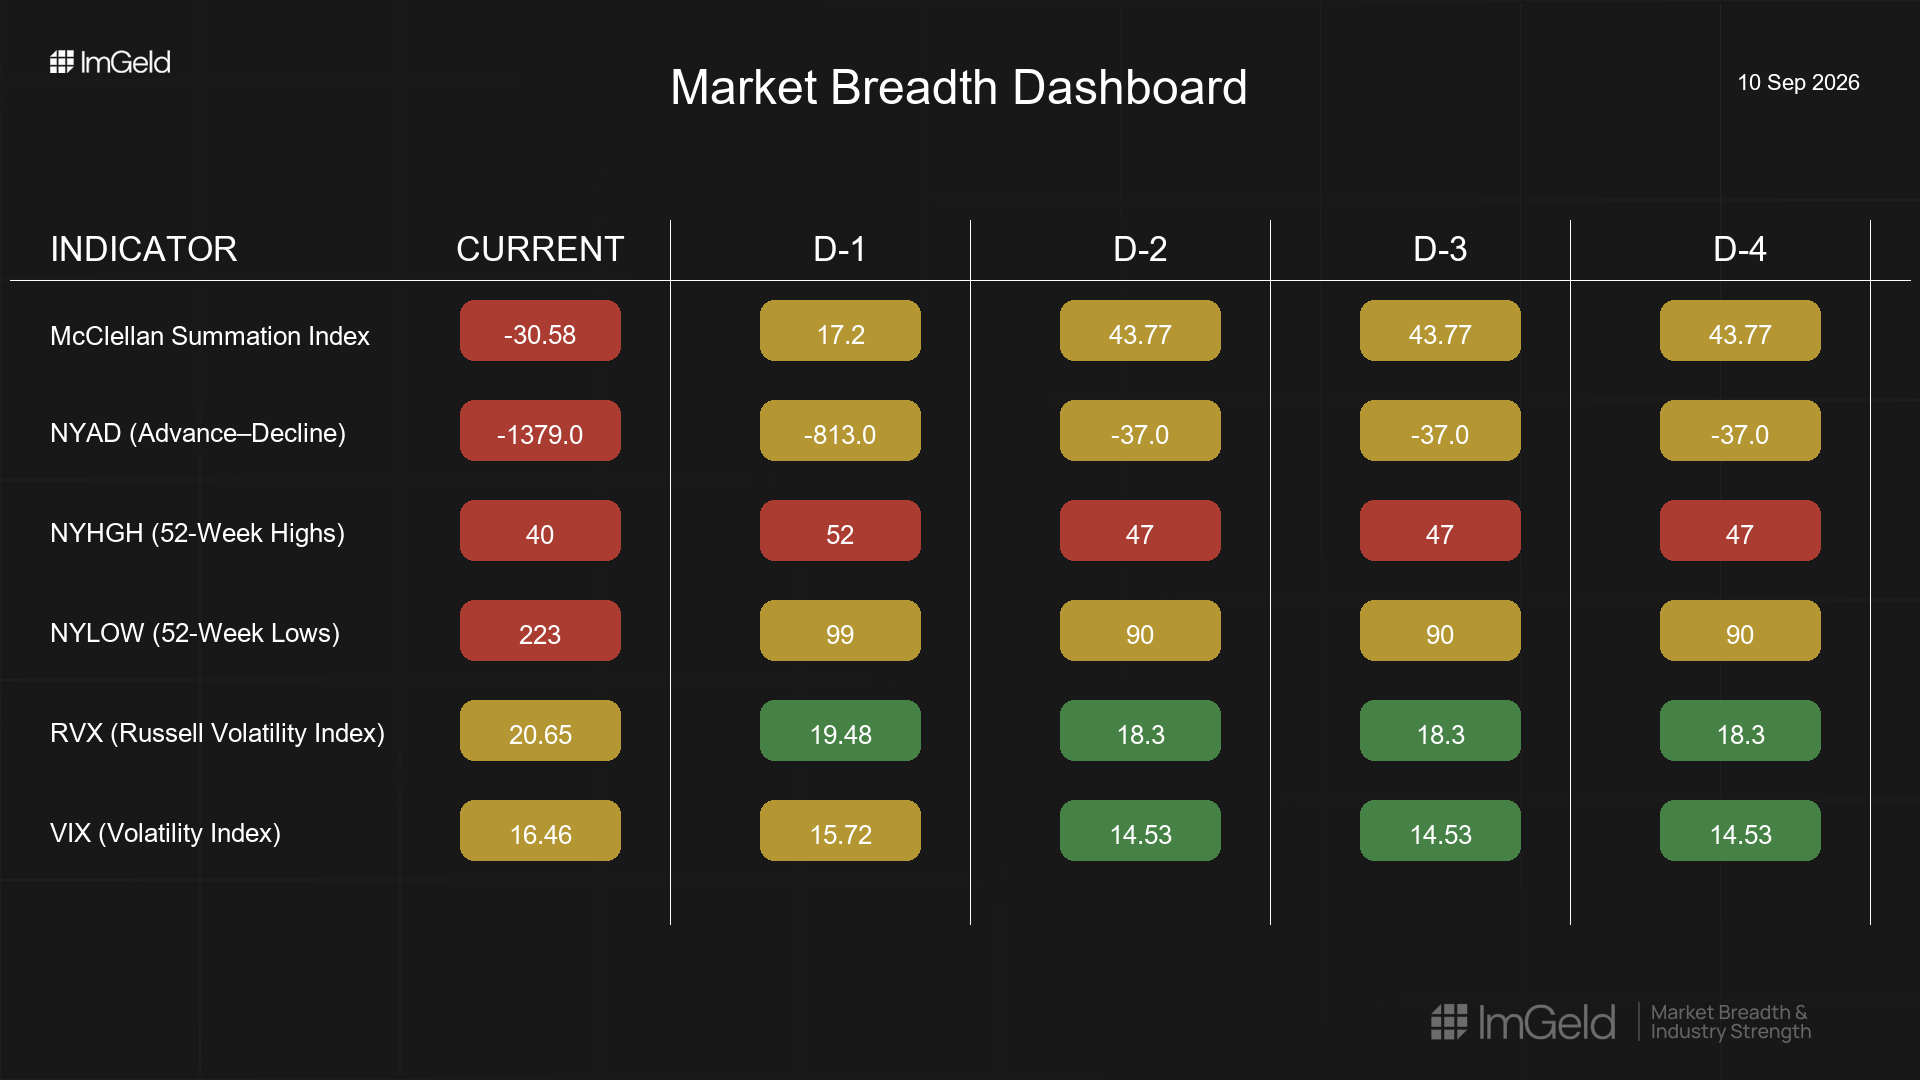
Breadth deteriorated sharply over the last five sessions. NYSI (McClellan Summation Index) fell from 43.77 to -94.17, confirming a decisive downside reversal. NYAD (Advance–Decline Line) stayed negative throughout, troughing at -1,379 and finishing at -1,266. Volatility expanded, with VIX (CBOE Volatility Index) rising to 17.84 and RVX (Russell Volatility Index) to 22.44.
Tactically, any long opportunity is highly selective and limited to resilient mid-cap industries showing relative strength and stable estimate revisions. Short setups remain valid, particularly in large-cap leadership where participation is thinning and in cyclically sensitive groups losing breadth. Selectivity is high until NYAD stabilizes and new lows contract
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing firmly across five sessions, with leadership becoming more concentrated. Volatility is expanding, led by RVX, which indicates rising pressure across small and mid-cap universes. There is no favorable divergence between NYSI and NYAD; both confirm deterioration. The five-day pattern signals continuation rather than early accumulation, though the surge in new lows introduces the possibility of late-phase weakness rather than an immediate bottom. By the five-day consistency rule, breadth weakness is firmly in control.
Indicator Breakdown
NYSI (McClellan Summation Index) Structure is firmly declining. The index transitioned from positive to deeply negative, with downside momentum accelerating into 2026-09-11.
NYAD (Advance–Decline Line) Daily participation weakened persistently. Negative readings each session, with deep cumulative declines mid-week and only marginal improvement by week end, indicate broad selling pressure.
NYHGH (New 52-Week Highs) Leadership expansion is absent. Highs were flat to softer, oscillating around the mid-40s and failing to expand despite index-level volatility, signaling narrow leadership.
NYLOW (New 52-Week Lows) Downside pressure is rising. New lows expanded from 90 to 353, reflecting stress across multiple industries and poor risk appetite.
Volatility Regime VIX advanced from 14.53 to 17.84 and RVX from 18.30 to 22.44. The rising RVX premium over VIX signals greater fragility in small and mid-caps. An expanding volatility regime favors disciplined risk management, patient entry timing, and a bias to fade weak bounces in over-owned large-cap leadership.
Tactical Implications
Longs: Only in selective mid-cap industries with demonstrated relative strength, durable cash flows, and defensive characteristics such as regulated utilities, specialty insurance, and mission-critical aerospace and defense suppliers. Stagger entries and demand confirmation from contracting new lows.
Shorts: Remain valid in large-cap growth-heavy industries where participation is thinning, notably consumer internet and semiconductors, and in cyclical mid-caps making fresh lows.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.