

Executive Summary Date: 2026-10-07
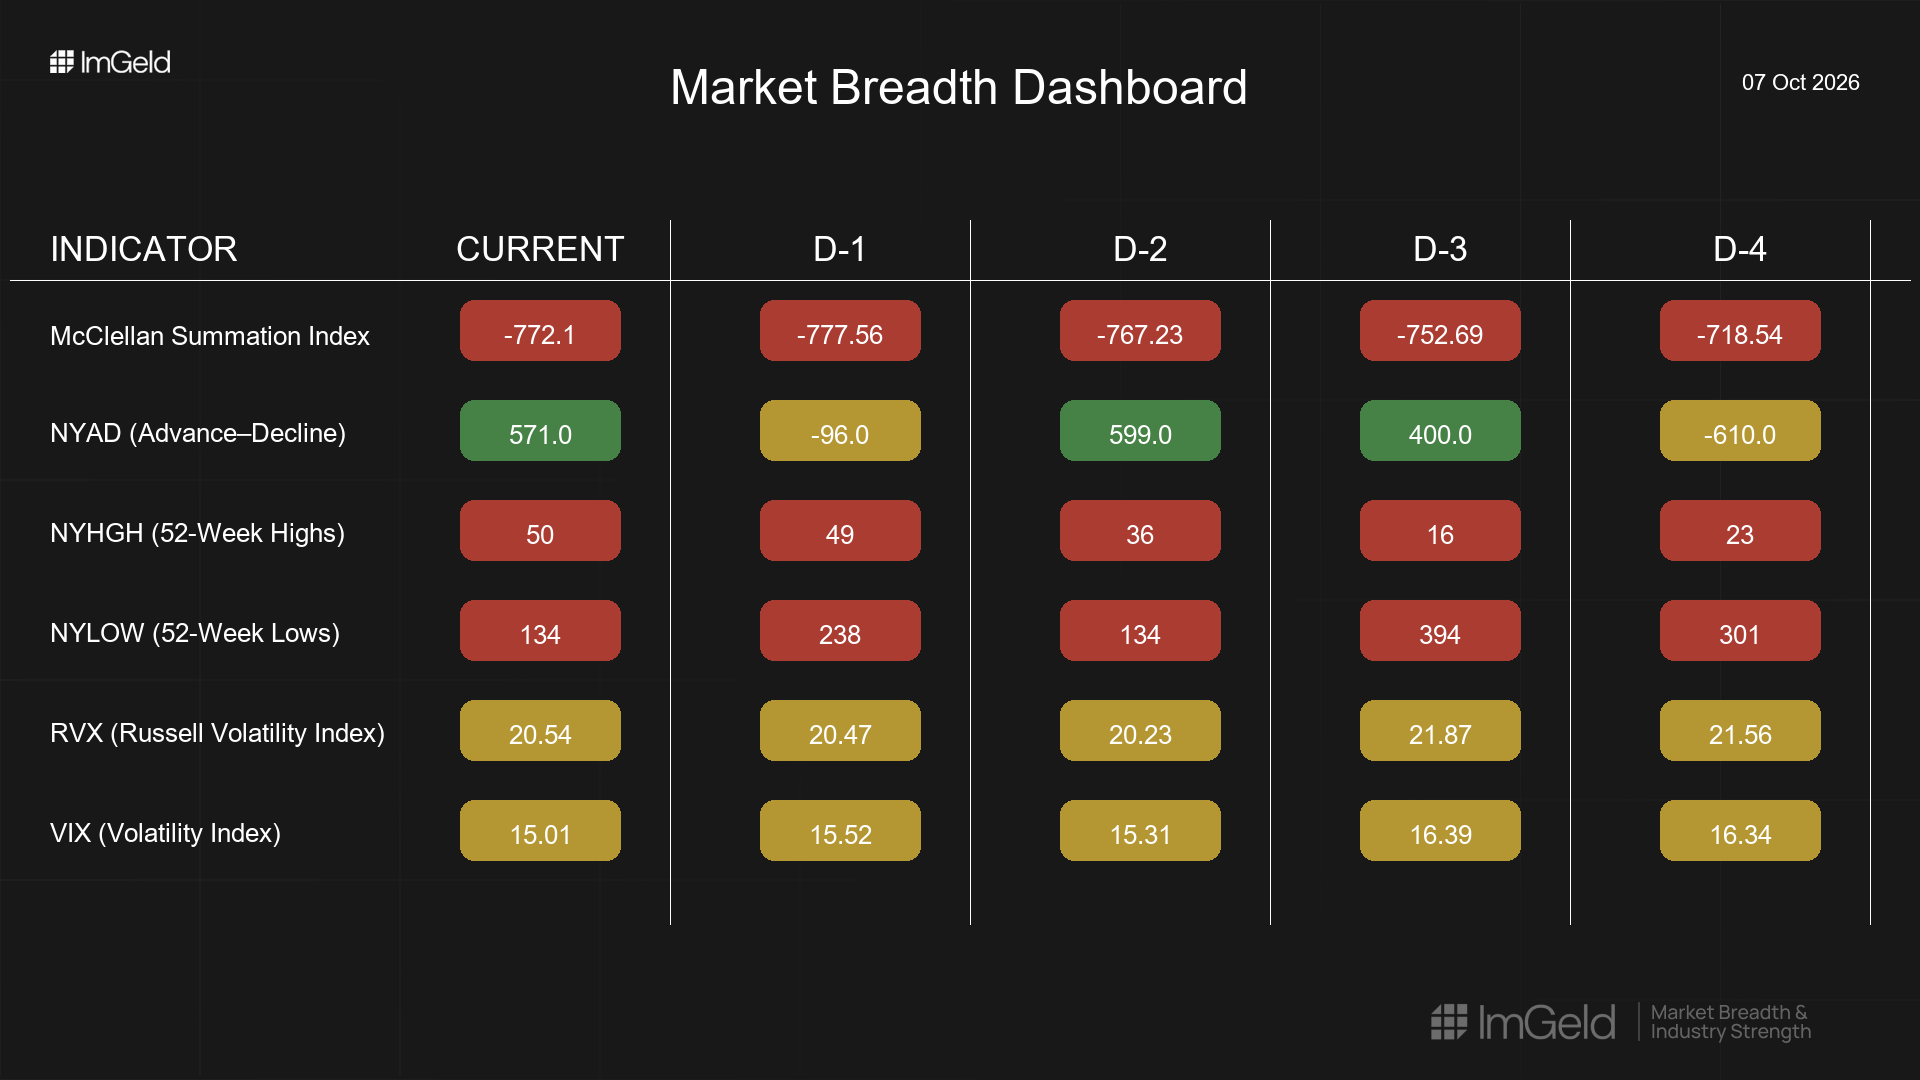
Breadth shows an early stabilization attempt. NYSI (McClellan Summation Index) remains deeply negative and fell for four sessions before a modest uptick today. NYAD (Advance–Decline Line) skewed positive on three of five sessions, indicating intermittent accumulation. Volatility compressed with VIX (CBOE Volatility Index) drifting toward 15 and RVX (Russell Volatility Index) easing near 20, supportive of tactical risk-taking but still signaling dispersion.
Selectivity remains high. Emerging long opportunities favor mid-cap industries where new highs are expanding and new lows are receding. Short setups remain valid in large-cap industries with weakening breadth or persistent new-low pressure.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is attempting to broaden: NYAD printed three positive days and NYHGH rose steadily while NYLOW declined from elevated levels. Leadership is beginning to rotate away from an exclusively large-cap profile toward more mid-cap participation, though concentration risk is not fully resolved given NYSI’s still-declining structure. Volatility is compressing, which typically aids follow-through, yet the NYSI and NYAD divergence highlights a countertrend rally within a negative intermediate backdrop. The five-day pattern signals early accumulation but remains tentative due to mixed signals.
Indicator Breakdown
NYSI (McClellan Summation Index) Structure declined from -718.54 to -777.56 across four sessions, then improved marginally to -772.10. Trend remains down with a nascent attempt to base. Confirmation requires additional positive breadth days.
NYAD (Advance–Decline Line) Daily reads were -610, +400, +599, -96, +571. Net positive over five sessions with two setbacks. Participation improved, but the reversals indicate uneven conviction.
NYHGH (New 52-Week Highs) Rising from 23 to 50 across the period. Leadership is expanding off a low base, consistent with emerging mid-cap strength.
NYLOW (New 52-Week Lows) Elevated early at 301 and 394, then improved to 134, a brief re-widening to 238, and back to 134. Downside pressure is easing but not fully abating.
Volatility Regime VIX moved 16.34 to 15.01 and RVX 21.56 to 20.54, indicating mild compression. The modest RVX premium points to ongoing dispersion and a favorable environment for selective positioning rather than broad beta.
Tactical Take
Longs: Focus on mid-cap industries showing improving leadership and relative strength such as industrial automation, electrical equipment, application software, and specialty insurance where new highs are advancing and lows are contained.
Shorts: Remain selective in large-cap industries with deteriorating breadth or heavy new-low profiles, including big-box retail, legacy media, diversified hardware, and integrated energy if momentum continues to falter.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.