

Executive Summary Date: 2026-08-21
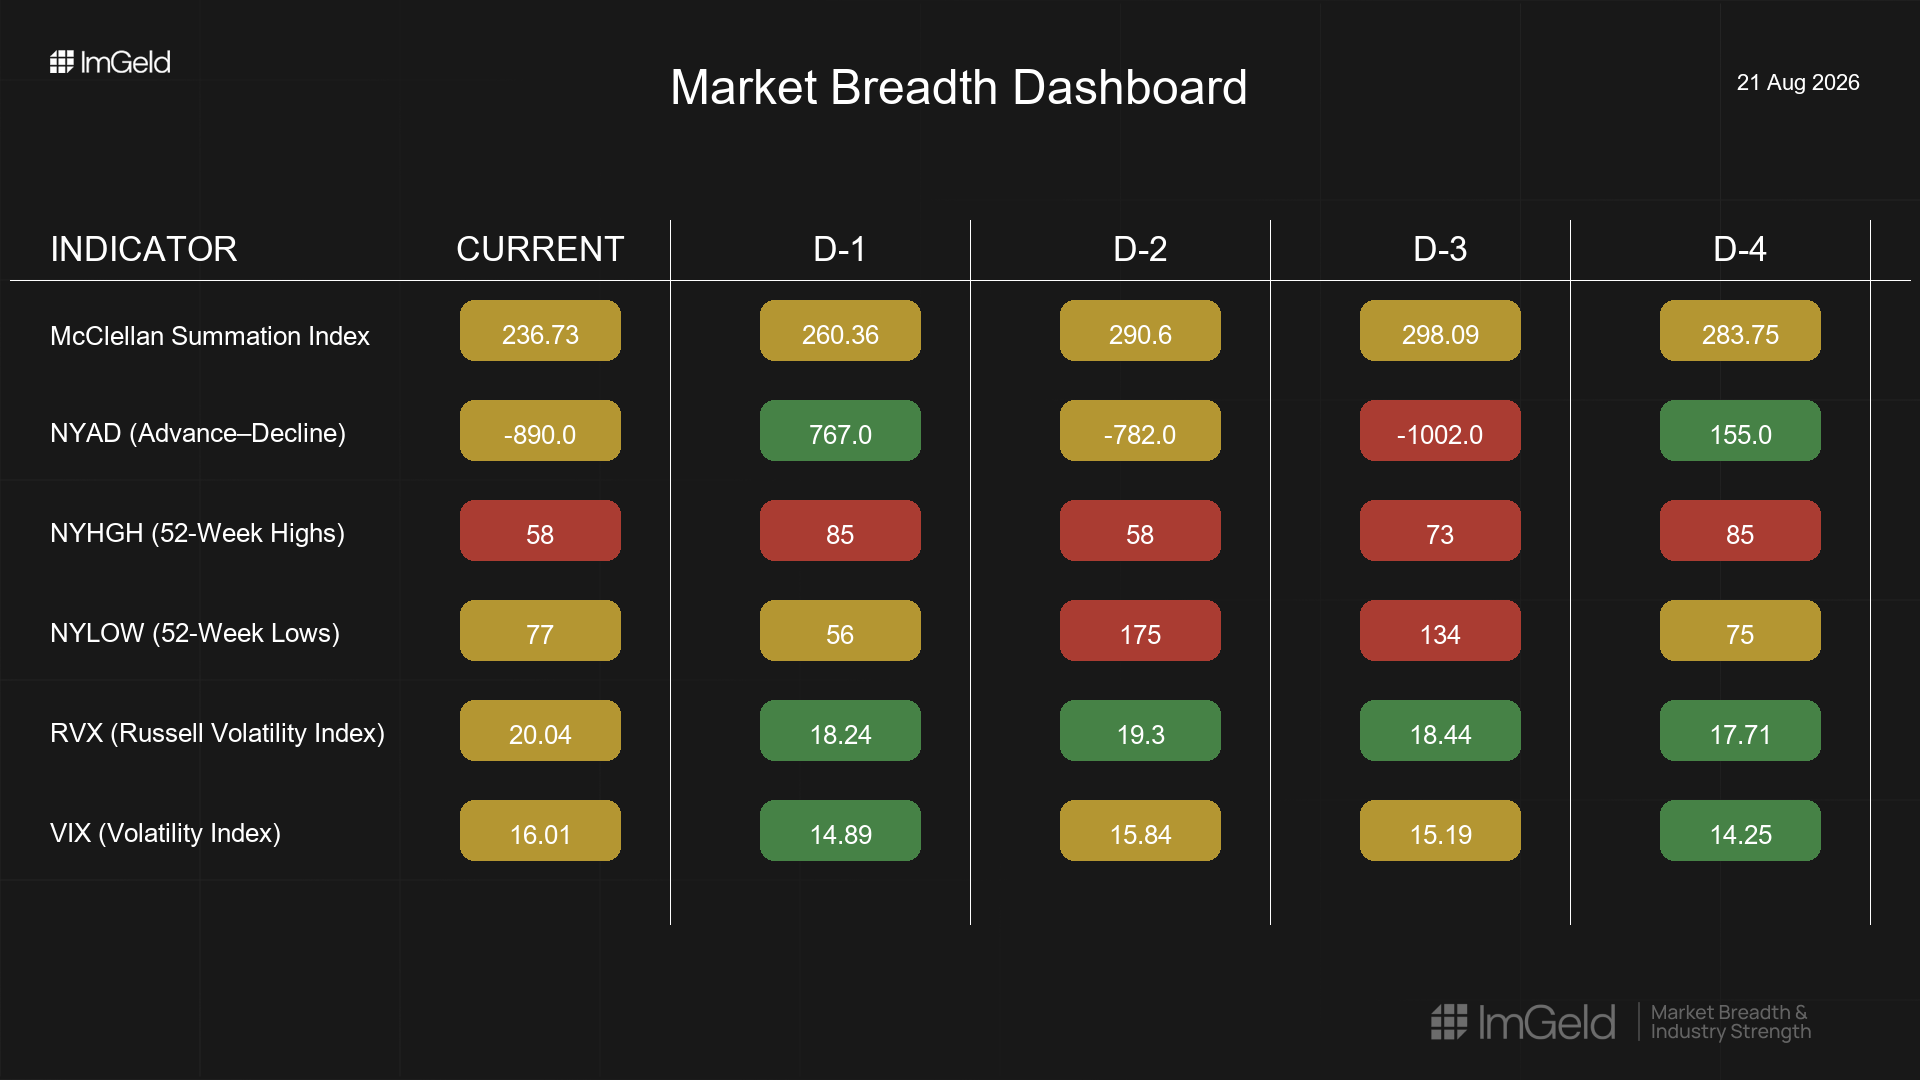
Breadth weakened over the last five sessions. NYSI (McClellan Summation Index) rolled over after a brief uptick, declining for three straight days into 236.73. NYAD (Advance–Decline Line) remained choppy but net negative, with three weak sessions including a sharp down day on 2026-08-20. Volatility expanded: VIX (CBOE Volatility Index) pushed to 16.01 and RVX (Russell Volatility Index) to 20.04, with the RVX–VIX spread widening, signaling rising small and mid-cap risk premia.
Tactically, long opportunities are emerging only selectively in resilient mid-cap industries showing stable highs and contained lows. Short setups remain valid in overextended large-cap industries where breadth is deteriorating and volatility is building. Selectivity is high.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing as leadership fails to expand and downside prints persist. Leadership appears increasingly concentrated, with NYHGH not sustaining progress and NYLOW staying elevated versus recent weeks. Volatility is firmly expanding across both VIX and RVX, with RVX leading. A brief NYAD rebound on 2026-08-19 did not alter the weakening NYSI trend, leaving a negative divergence resolved to the downside. By the five-day consistency rule: breadth deterioration is firmly in place (NYSI down three consecutive days), NYAD remains mixed with a bearish tilt, and the volatility regime is firmly expanding. The pattern points to early distribution/continuation rather than accumulation.
Indicator Breakdown
NYSI (McClellan Summation Index) Structure is declining: after peaking at 298.09 on 2026-08-17, NYSI fell to 236.73 by 2026-08-20. The downshift signals waning intermediate momentum and greater vulnerability to further breadth erosion unless buyers reassert quickly.
NYAD (Advance–Decline Line) Daily participation weakened on three of five sessions (notably -1002 and -890), partially offset by one strong up day (+767). Net breadth over the window is negative, indicating more issues declining than advancing on balance.
NYHGH (New 52-Week Highs) Leadership expansion is inconsistent. Prints oscillated (85, 73, 58, 85, 58), with no follow-through after brief strength. This points to narrow leadership unable to broaden beyond a small cohort.
NYLOW (New 52-Week Lows) Downside pressure remains active. Lows spiked early (134, 175), eased midweek (56), and rose again (77). Risk appetite is fragile; renewed lows would quickly embolden sellers.
Volatility Regime VIX advanced from 14.25 to 16.01 and RVX from 17.71 to 20.04, with the spread widening. This supports tighter risk controls, quicker trade horizons, and a bias to fade stretched rallies in weak breadth industries. For longs, prefer staggered entries only in mid-cap groups with clear relative strength.
Tactical Implications
Longs: Highly selective in mid-cap industries showing resilient internals, such as niche Software, Defense Electronics, Life Science Tools, and Specialty Chemicals where NYHGH is holding and NYLOW is muted.
Shorts: Favor deteriorating large-cap industries where participation is narrowing and volatility is rising, including Consumer Internet, Semiconductor Hardware, and Broadline Retail.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.