

Executive Summary Date: 2026-09-10
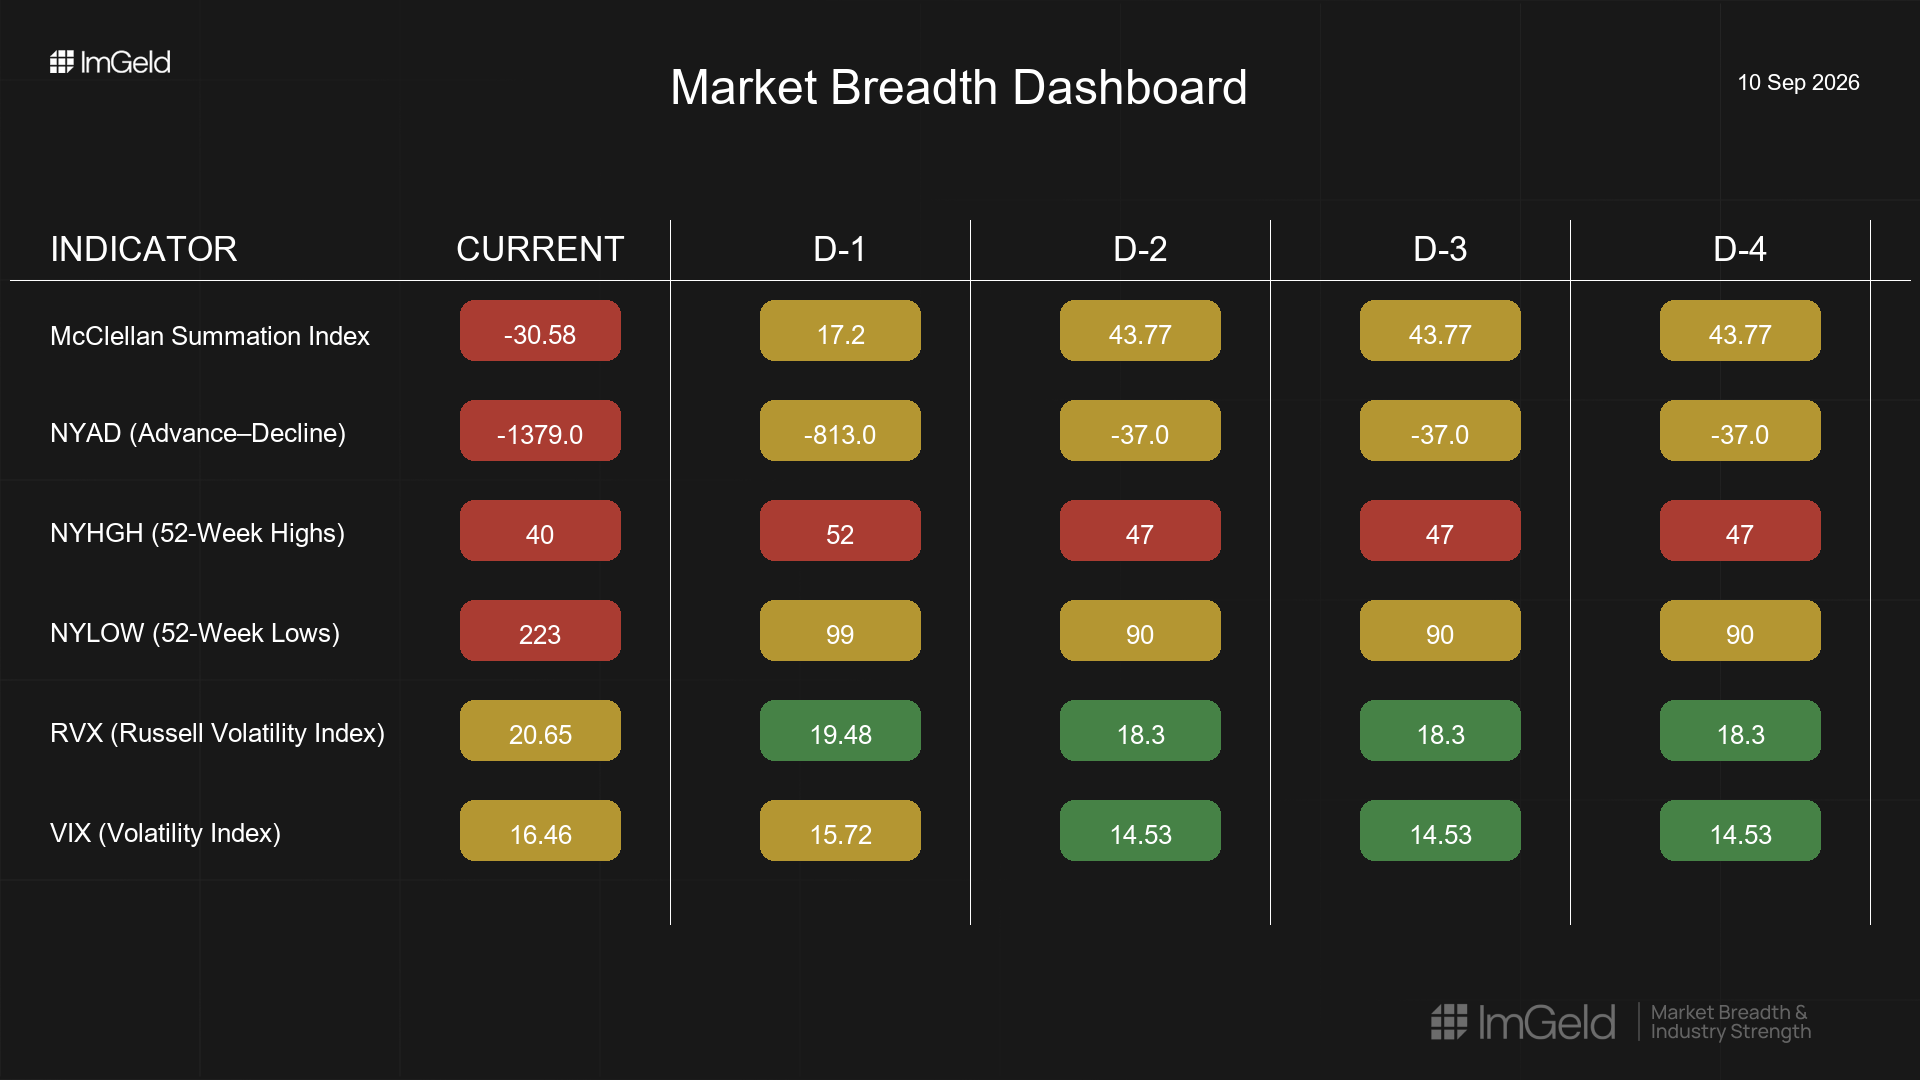
Breadth cracked lower over the last five sessions. NYSI (McClellan Summation Index) rolled from 43.77 to -30.58, while NYAD (Advance–Decline Line) deteriorated further to -1,379, confirming a broad-based downside impulse. Volatility expanded: VIX (CBOE Volatility Index) rose from 14.53 to 16.46 and RVX (Russell Volatility Index) from 18.30 to 20.65. Leadership faded as NYHGH (New 52-Week Highs) slipped to 40 and downside pressure intensified with NYLOW (New 52-Week Lows) jumping to 223.
Tactically, short opportunities remain valid, especially in high-beta, richly valued large caps within semiconductors, internet platforms, and consumer discretionary industries. Any long attempts should be highly selective and limited to resilient mid-cap industries with defensive cash flows and improving relative strength; patience is warranted until downside momentum cools and NYLOW contracts.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing and leadership is becoming more concentrated, then fading. Volatility is expanding. There is no constructive divergence: NYSI’s abrupt rollover now aligns with persistent NYAD weakness. Applying the five-day consistency rule, the last two sessions show consistent deterioration; the read is firmly risk-off with a continuation bias rather than early accumulation. The pattern resembles an acceleration, not exhaustion. A credible turn would require stabilization in NYAD and a higher low in NYSI.
Indicator Breakdown
NYSI (McClellan Summation Index) Early-week plateau near 43.77 gave way to 17.20 and then -30.58. Structure is decisively declining; momentum has turned negative.
NYAD (Advance–Decline Line) Persistent weakness escalated with -813 and -1,379 the last two sessions, indicating broad and intensifying sell pressure.
NYHGH (New 52-Week Highs) Brief uptick to 52 failed; back to 40. Leadership expansion stalled, indicating fragile upside participation.
NYLOW (New 52-Week Lows) Expanded from 90 to 223, marking rising downside risk and deteriorating risk appetite.
Volatility Regime VIX advanced to 16.46 and RVX to 20.65. The shift supports a net short tilt, tighter risk controls, and faster trade horizons. Elevated RVX relative to VIX warns against high-beta exposure without clear confirmation from breadth.
Industries focus: Maintain short bias in large-cap, growth-heavy industries exhibiting deteriorating breadth and crowding. For future longs, restrict to mid-cap names in defensive, cash-generative industries showing relative strength and stable accrual quality, and wait for breadth stabilization.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.