

Executive Summary Date: 2026-09-15
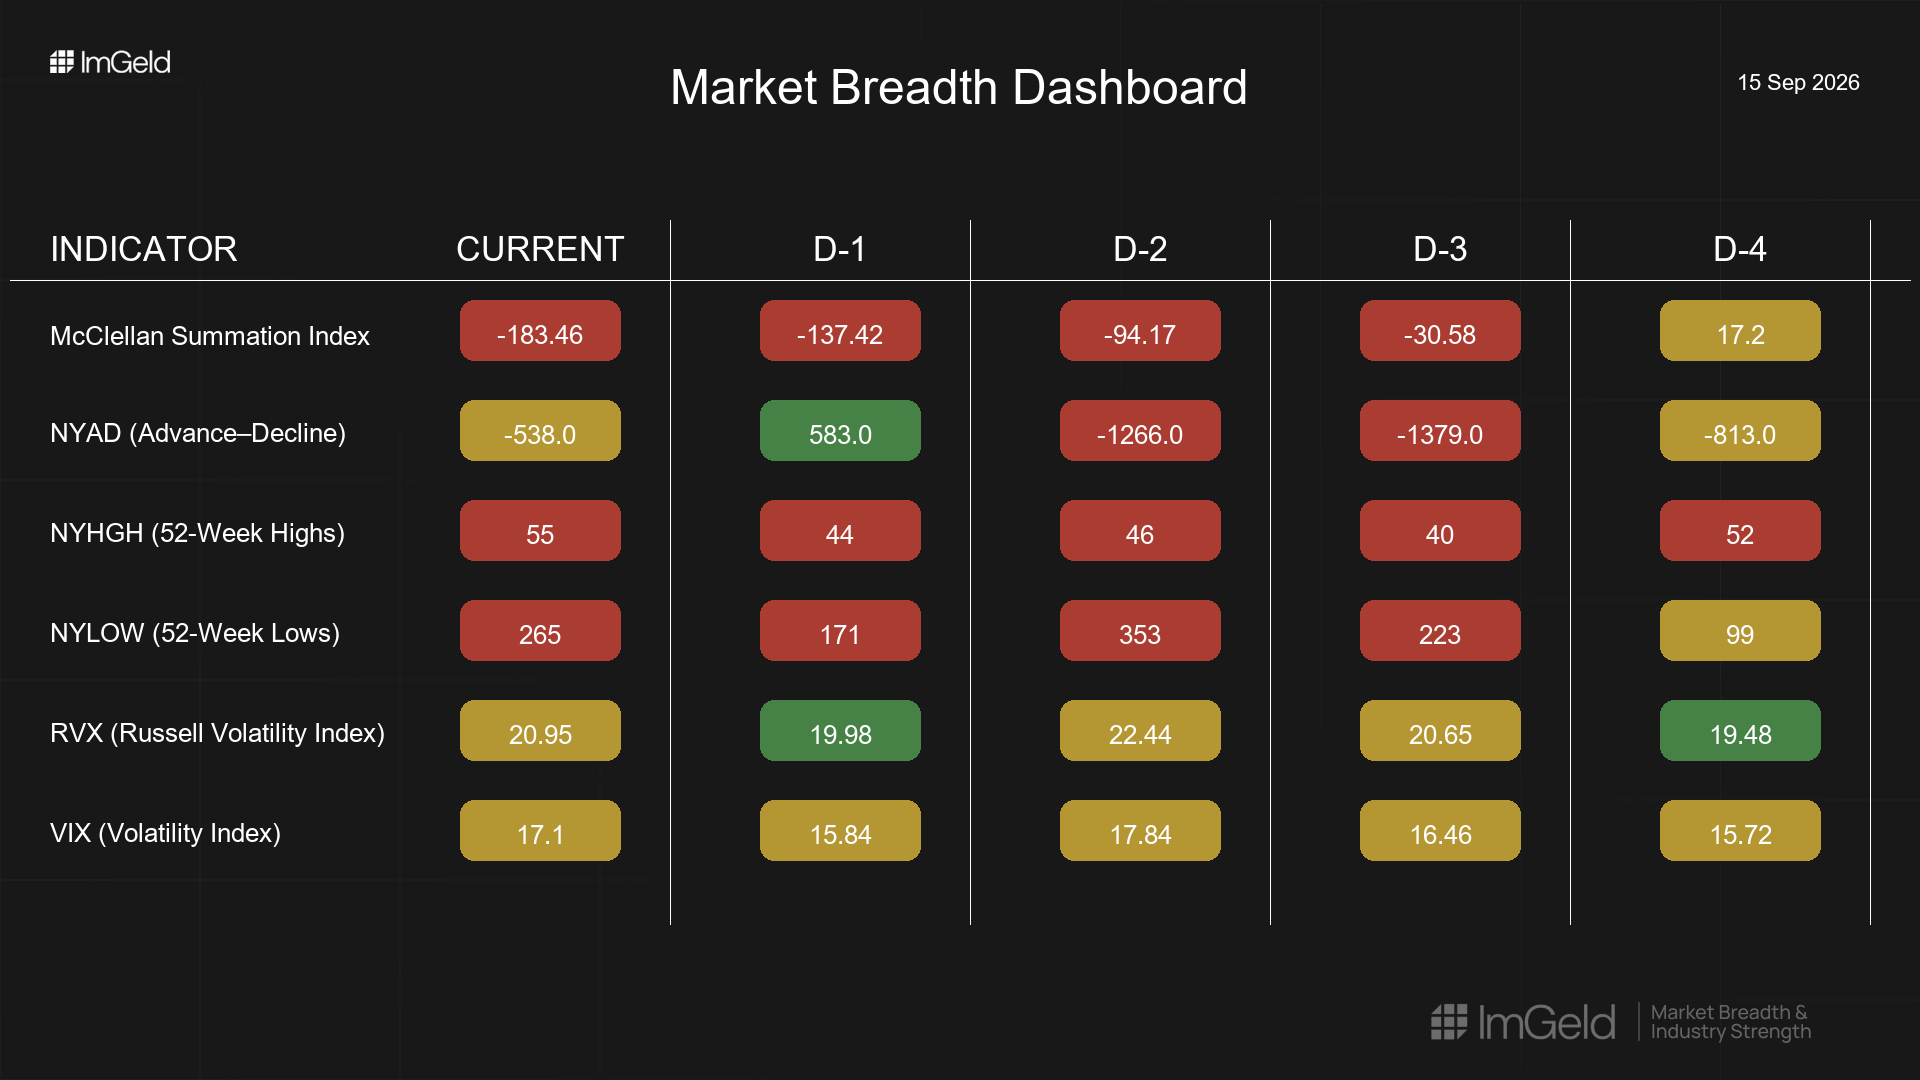
Breadth deteriorated across the last five sessions. NYSI (McClellan Summation Index) flipped from +17.2 to -183.5, confirming a persistent downside impulse. NYAD (Advance–Decline Line) was negative on four of five days, with a brief countertrend uptick on 09-14 that failed to carry. Volatility firmed, with VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) both rising net over the period and oscillating intraday.
Tactically, any long attempts should be highly selective and limited to resilient mid-cap industries demonstrating relative strength and stable cash flows. Short opportunities remain valid in large caps where leadership is crowded and breadth fatigue is visible; prioritize names showing weakening participation and expanding realized volatility.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing: declines outpaced advances on most days, NYLOW remained elevated, and leadership appears more concentrated despite a small uptick in NYHGH. Volatility is expanding rather than compressing, with both VIX and RVX stepping higher after failing to sustain the 09-14 pullback. A minor divergence emerged as NYAD briefly improved on 09-14 while NYSI continued to slide, indicating that buying interest was episodic and not yet structural. By the five-day consistency rule, the negative breadth impulse is firmly in place (4 of 5 days), while the single constructive session is tentative. The pattern points to continuation of distribution with only early, unconfirmed signs of potential stabilization.
Indicator Breakdown
NYSI (McClellan Summation Index) Sequential declines each session, moving decisively deeper negative. No evidence of basing; momentum remains lower.
NYAD (Advance–Decline Line) Weak participation on 09-09, 09-10, 09-11, and 09-15. The 09-14 improvement (+583) lacked follow-through and was reversed the next day, reinforcing a weakening breadth backdrop.
NYHGH (New 52-Week Highs) Stable, low-level prints with a modest uptick to 55 on 09-15. This suggests isolated leadership but not a broad expansion.
NYLOW (New 52-Week Lows) Elevated throughout, peaking at 353 on 09-11 and remaining high at 265 on 09-15. Downside pressure persists; risk appetite is constrained.
Volatility Regime VIX rose from 15.7 to 17.1 and RVX from 19.5 to 21.0 across the period, with choppy swings. The upward bias in both indices indicates unresolved risk and supports a disciplined, selective approach to entries and sizing.
Tactical Implications
Long side: Only in select mid-cap industries with defensive cash generation and relative strength (for example, regulated utilities, specialty insurers, waste and niche infrastructure services). Prefer names printing new relative highs against their industry cohorts.
Short side: Large caps remain suitable for shorts where positioning is crowded and breadth is deteriorating, especially in cyclically sensitive or momentum-heavy leadership showing volatility expansion and failed breakouts.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.