

Executive Summary Date: 2026-09-29
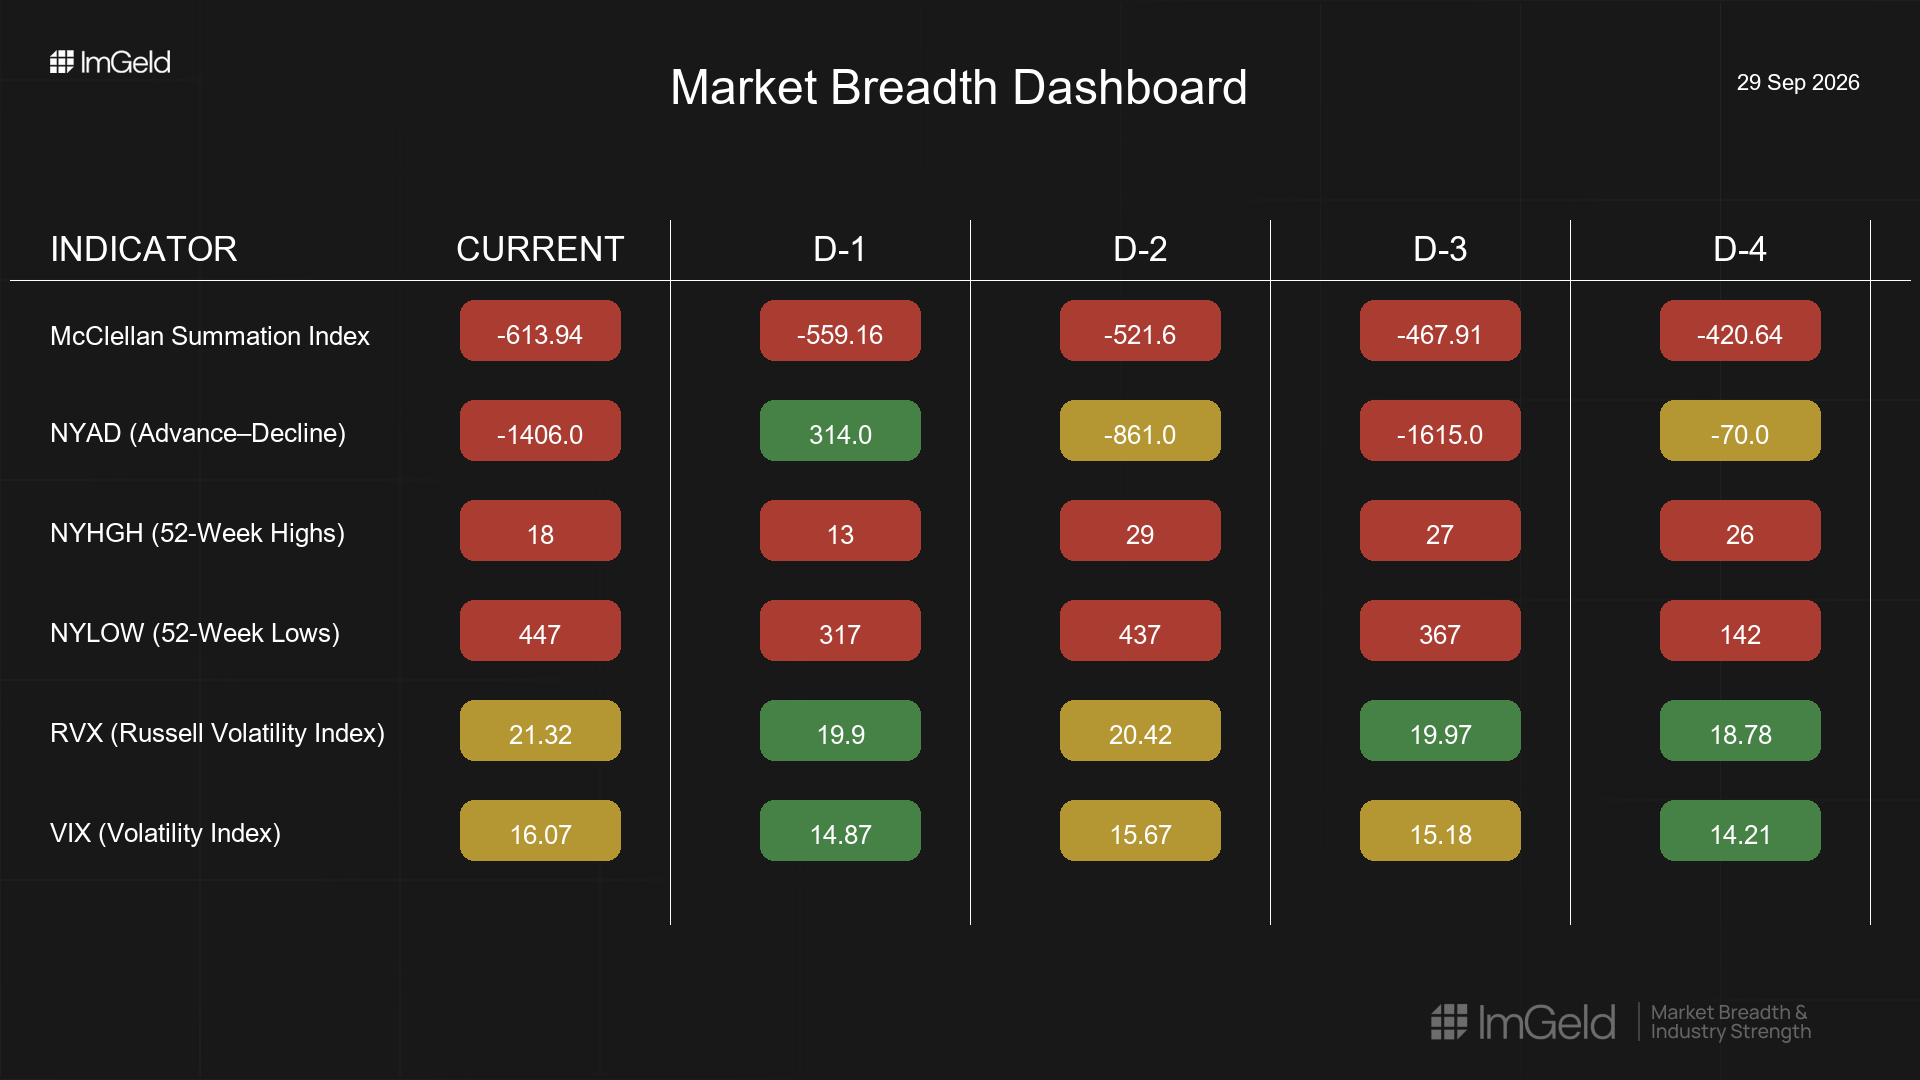
Breadth deteriorated over the last five sessions. NYSI (McClellan Summation Index) fell each day to -613.94, confirming persistent downside momentum. NYAD (Advance–Decline Line) printed four negative days with one isolated positive on 09-28, signaling weak participation with only tentative countertrend interest. Volatility firmed: VIX (CBOE Volatility Index) advanced to 16.07 and RVX (Russell Volatility Index) to 21.32, with RVX outpacing VIX, consistent with rising risk premia in smaller capitalization universes.
Tactically, short setups remain valid, particularly in vulnerable large-cap growth industries and economically sensitive cyclicals. Any long exposure should be highly selective and confined to mid-cap industries showing relative strength and resilient cash flows; evidence is early, not actionable at scale.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing, with leadership becoming more fragile as NYHGH (New 52-Week Highs) contracted into the teens and NYLOW (New 52-Week Lows) expanded toward recent highs. Volatility is expanding rather than compressing, with RVX’s premium over VIX widening, a bearish breadth tell. A minor divergence appeared on 09-28 when NYAD turned positive while NYSI continued to decline, but this was a single-day event and therefore tentative. Applying the five-day consistency rule: NYSI is firmly lower; NYAD is firmly weak with one tentative countertrend day. The five-day pattern supports continuation of downside pressure rather than early accumulation, and warns of exhaustion risk only if volatility spikes markedly without further deterioration in lows.
Indicator Breakdown
NYSI (McClellan Summation Index) Firmly declining across all five sessions, deepening negative territory and confirming a sustained deterioration in intermediate breadth.
NYAD (Advance–Decline Line) Breadth weakened on 09-23, 09-24, 09-25, and 09-29, interrupted by a single positive day on 09-28. Net participation remains skewed to decliners, consistent with distribution.
NYHGH (New 52-Week Highs) Compressed from 29 to the mid-to-high teens by 09-29, indicating no leadership expansion and limited risk appetite for breakouts.
NYLOW (New 52-Week Lows) Elevated and rising into 447 on 09-29 after a brief dip, signaling persistent downside pressure and broadening sell lists.
Volatility Regime VIX advanced from low-14s to just above 16; RVX rose from high-18s to above 21. The upward drift and RVX leadership suggest stress is building more in small and mid-cap cohorts, warranting disciplined risk control and respect for gap risk.
Tactical Takeaways
Shorts: Remain focused on large-cap growth industries with crowded positioning and deteriorating breadth (e.g., software platforms, semiconductors) and on cyclical industries exposed to slowing demand (e.g., discretionary retail, transports).
Longs: If initiated, restrict to selective mid-cap industries showing relative strength and stable cash flows (e.g., regulated electric utilities, midstream energy infrastructure, specialty insurers), sized cautiously pending stabilization in NYLOW and a turn in NYAD.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.