

Executive Summary Date: 2026-09-22
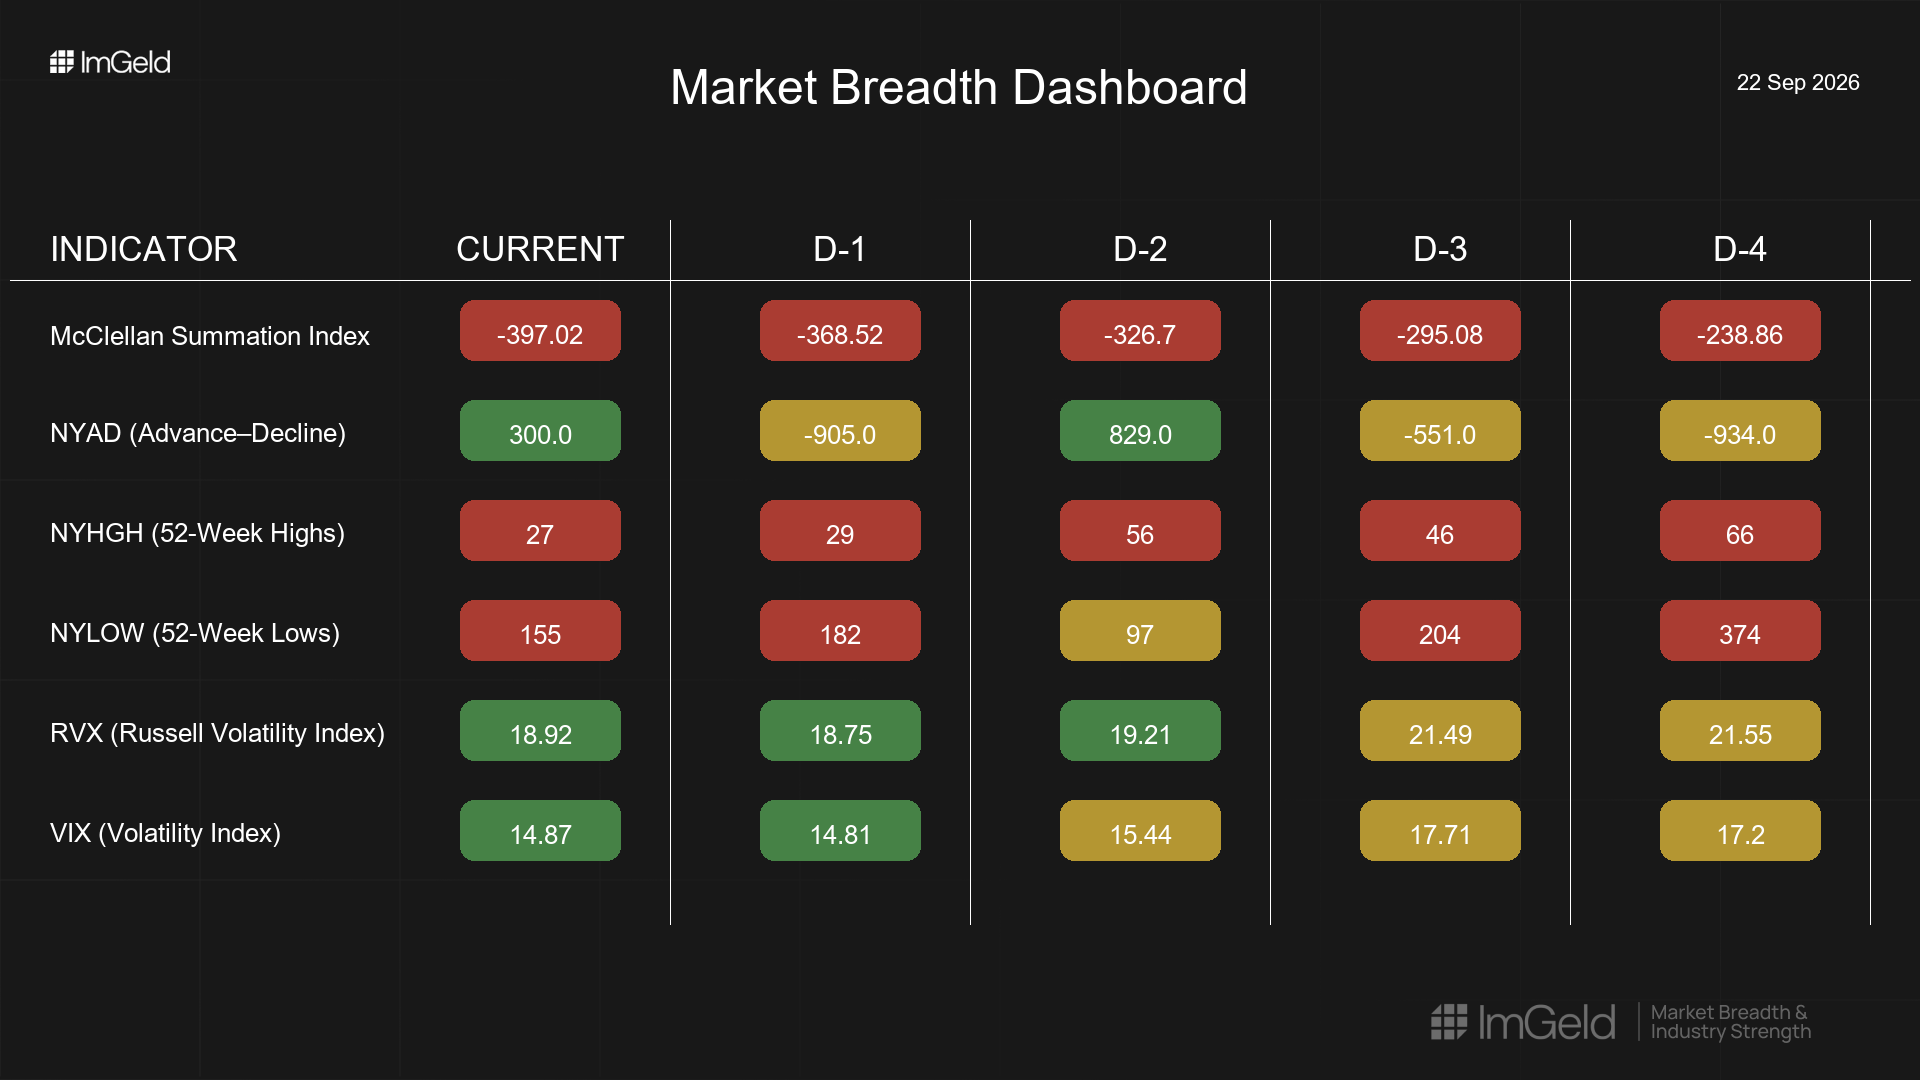
Breadth weakened over the last five sessions. NYSI (McClellan Summation Index) declined steadily deeper into negative territory, while NYAD (Advance–Decline Line) remained volatile with a net negative tilt despite two positive prints. Volatility compressed as VIX (CBOE Volatility Index) and RVX (Russell Volatility Index) trended lower, signaling complacency risk. Tactically, maintain a tentative short bias. Short opportunities remain valid in index-heavy large caps and in industries showing persistent new-low pressure. Longs, if any, should be highly selective and confined to mid-cap industries demonstrating relative strength, stable bid, and improving up/down volume trends.
Get the Industry Heat Map — delivered by email only.
Global Read
Participation is narrowing and leadership is becoming more concentrated, with new highs fading and new lows outnumbering highs throughout the window. Volatility has compressed across VIX and RVX, though RVX’s slight uptick today hints at emerging stress beneath the surface. A divergence is evident: NYSI is firmly deteriorating, while NYAD is mixed with intermittent rebounds that have not changed the broader negative structure. By the five-day consistency rule, deterioration in NYSI is Firm, volatility compression is Firm, while NYAD remains Mixed. The five-day pattern signals continuation of distribution with tentative rally attempts rather than early accumulation.
Indicator Breakdown
NYSI (McClellan Summation Index) Firm deterioration across all five sessions (-238.86 to -397.02), confirming weakening internal momentum and a negative intermediate setup.
NYAD (Advance–Decline Line) Participation remains mixed: -934, -551, +829, -905, +300. Despite two positive days, the sequence skews negative, indicating fragile rebounds within a broader deterioration.
NYHGH (New 52-Week Highs) Leadership expansion is contracting (66, 46, 56, 29, 27). Highs are subdued and fading, pointing to narrowing leadership and limited upside sponsorship.
NYLOW (New 52-Week Lows) Downside pressure remains elevated (374, 204, 97, 182, 155). While off the peak, lows persistently exceed highs, reflecting weak risk appetite and ongoing distribution.
Volatility Regime VIX compressed from 17.71 to 14.87; RVX from 21.55 to 18.92 with a modest final-day uptick. This favors tactical fade-the-bounce setups, as low implieds can mask downside gap risk if breadth weakens further.
Tactical Takeaway
Shorts: Continue to prioritize rallies in index-heavy large caps and in industries with rising new lows and deteriorating advance–decline profiles.
Longs: Only consider highly selective mid-cap opportunities in resilient industries (e.g., insurance carriers/brokers, waste and environmental services, niche infrastructure software) showing improving relative strength and suppressed new lows. Keep risk tight and time entries to breadth confirmation days.
Access the ImGeld Fundamental Report
Stay informed. Unlock the ImGeld Industry Updates — subscribers only.